


SNAPSHOT OVERVIEW
THE OPPORTUNITY
The FY2027 President’s Budget requests approximately $1.5 trillion in combined defense authority, the largest since World War II. Total RDT&E: $343.7 billion. Total O&M: $382.6 billion discretionary.
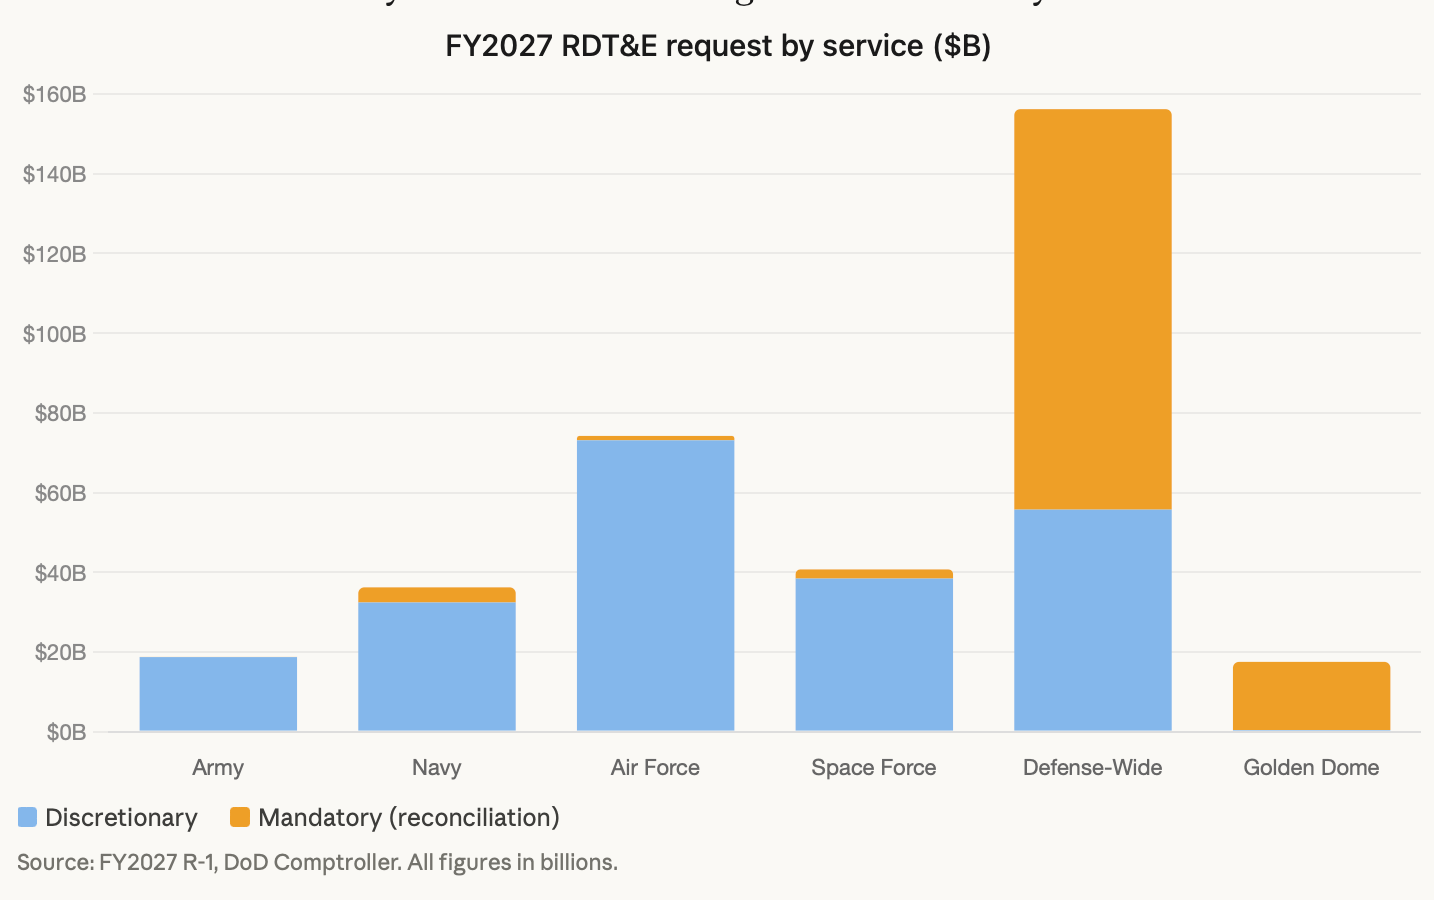
The Golden Dome for America Fund adds $17.5 billion in mandatory RDT&E under a new standalone appropriation (Account 3007D). Space Force RDT&E jumps 159% to $38.4 billion. Air Force requests $73.1 billion, up 45%. This report maps which lines are funded, which are growing, and what type of vendor each program office is set up to engage.
MARKET AND SECTOR
Three compounding themes define this budget.
Legacy recapitalization: Sentinel ICBM deep in EMD. MV-75 replacing the Black Hawk. Artillery Systems EMD jumps 824% to $709 million for the new Mobile Tactical Cannon.
Autonomous systems: F-47 at $5 billion. CCA procurement appears for the first time at $996.5 million. Launched effects at $816 million, up 119%.
Homeland defense: Golden Dome spans MDA, Army, Air Force, Space Force, and DARPA. Missile defense PEs up ~127% in aggregate.
The signal here: Air Force at $73.1B and Space Force at $38.4B are the fastest-moving accounts. If your technology touches either domain, this budget is your addressable market.
FEDERAL MARKET TRANSFORMATION
Duffey’s Acquisition Transformation Strategy has eliminated 2,700 FAR and DFARS mandates. DIU fielding carries $434 million for non-traditional pathways. The Digital Transformation Office (PE 0606005F) grows 150% to $183.4 million. BA 8 continues expanding as the lowest-barrier channel for commercial vendors.
The January 2026 Executive Order prohibits underperforming contractors from stock buybacks until they deliver. That creates institutional cover for program offices to look at alternatives.
PRIMARY TAKEAWAY
The R-1, O-1, and M-1 are the most precise publicly available demand signal the DoW publishes. Almost no small business or BD team reads them systematically. This report does just that: structured analysis of what is funded, at what stage, through which contracting org, and where solicitations will emerge.
The appropriations window is open now.
WHO THIS SERVES
The FY2027 DoW defense budget is a 1.5-trillion-dollar document set. Those who could benefit most from reading it never do, not because they lack the capability, but because the documents were not written to be accessible to anyone outside the appropriations and acquisition system.
This report is a structured reading of those documents, written for the people who are trying to build companies, pursue new opportunities, and close contracts in the defense market including:
BD and Capture Teams at Small and Mid-Size Startups & Companies. You are trying to identify which program offices have funding and are likely to issue solicitations in FY2027. This issue maps which program elements grew, which contracted, and where the new money landed, so you can prioritize your pipeline before the RFPs are posted, not after.
Startups and Non-Traditional Vendors. You are evaluating whether and how to engage the DoW as a customer. This issue specifically identifies which programs are structured to engage commercial and non-traditional sources through OTA, SBIR, DIU Commercial Solutions Openings, and APFIT pathways, the acquisition mechanisms that do not require you to have navigated a traditional prime relationship first.
Defense-Focused Investors and Family Offices. You are looking for investment theses grounded in funded demand signals rather than press releases. The R-1 and P-1 books provide the most specific demand data available for any defense technology market, specific program names, appropriation levels, contracting agencies, and year-over-year trajectories. This issue compiles that data into investable signal.
Program Office and Acquisition Workforce. You want to understand how your specific programs fit into the broader budget context, what the cross-service comparisons look like, which peer programs are growing, and where the broader DoW posture is shifting. The landscape tables in this issue provide that orientation.
Government Affairs and Policy Teams. You are tracking which programs survived, grew, or were cut in the transition from FY2026 enacted to FY2027 request, and what those movements signal about DoW priorities heading into the authorization and appropriations cycle. The year-over-year data in this issue gives you that foundation.
HOW THIS ANALYSIS WORKS
Each issue of STARTUP DoD follows a structured framework built around primary government sources. This issue is fundamentally about how to read defense budget books, and how to translate what you find there into pipeline. I do not rely on press releases or secondary reporting as the first layer. I start with the documents and use everything else to interpret what I find there. For this issue, the process runs five layers deep.
R-1 Budget Detail Analysis. Line-by-line review of the FY2027 President’s Budget Exhibit R-1, released April 2026, covering Army, Navy, Air Force, Space Force, and Defense-Wide RDT&E program elements. Each program element is analyzed with year-over-year comparison against FY2026 enacted and FY2025 actuals, looking for trajectories that signal acceleration, deceleration, or new line creation. New lines that did not exist in FY2026 get separate attention because a new program element is often the first visible signal of a new contract vehicle.
O-1 Mission Area Mapping. Structured review of the O-1 exhibit to identify which budget activities and mission areas are growing versus contracting. The O-1 is underused by most BD analysts because it covers operations rather than development. But O&M growth in a mission area, particularly Cyberspace Activities, Space Operations, and Combat Operations Support, is a leading indicator of follow-on procurement and service contract demand.
M-1 Workforce Signal Reading. Analysis of military personnel funding trends by service as a leading indicator of operational emphasis. Where headcount is growing, training requirements follow. Where force structure is changing, as it is in Space Force (13,200 authorized in FY2027, up from 10,657), new contract lines for personnel support, facilities, and mission systems follow.
USAspending.gov Historical Award Cross-Reference. Review of recent awards (FY2025-FY2026) under relevant NAICS codes and program element numbers to identify who currently holds contracts in funded program areas. Historical award data tells you who the program office has already trusted, and what NAICS codes and PSC codes they used to find those vendors.
SAM.gov Active Solicitation Mapping. Identification of pre-solicitations, sources sought, and open solicitations that correspond to program elements with significant FY2027 funding increases. The R-1 program element number is the direct bridge between the budget exhibit and the solicitation. When a PE number appears in a SAM.gov posting, that is the budget line showing up as a contract opportunity.
WHAT ARE THE FY2027 BUDGET BOOKS, AND WHY DO THEY MATTER?
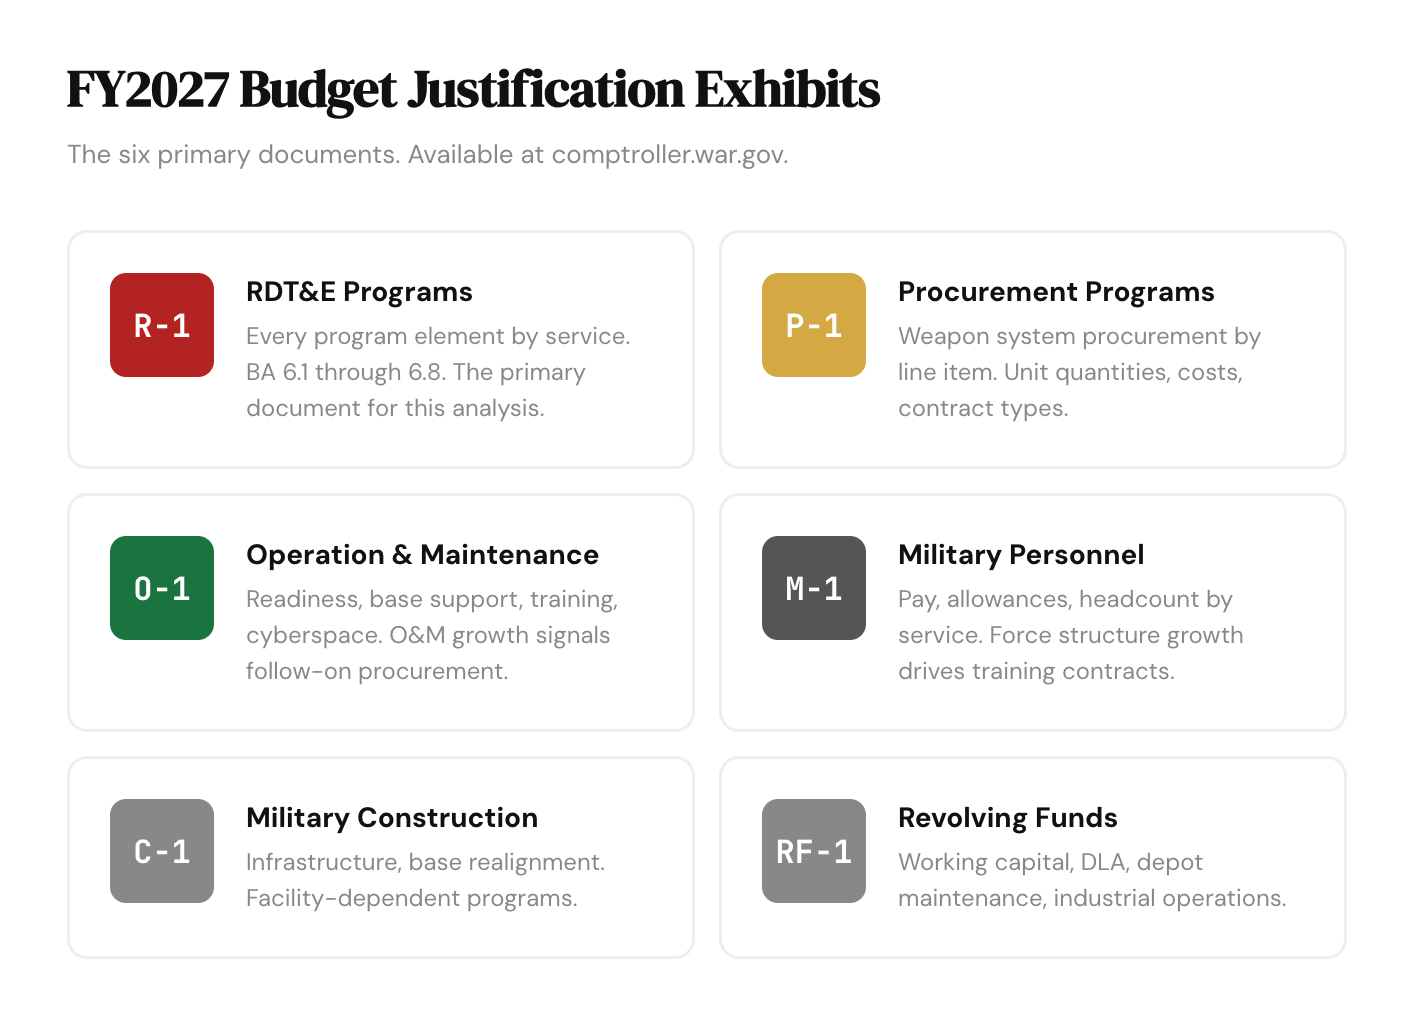
Every year, the Department of War submits a Presidential Budget request to Congress. Coincident with that submission, the Office of the Under Secretary of War Comptroller publishes a series of detailed justification exhibits named “the budget books,” that break down every appropriation by component, mission area, and program element. These are public documents available at comptroller.war.gov. For FY2027, the President’s Budget was released in April 2026.
The documents released for FY2027 include:
Within the R-1, each program element is categorized by Budget Activity (BA). This taxonomy tells you where a program is in its acquisition lifecycle, and therefore what type of vendor it is looking for.
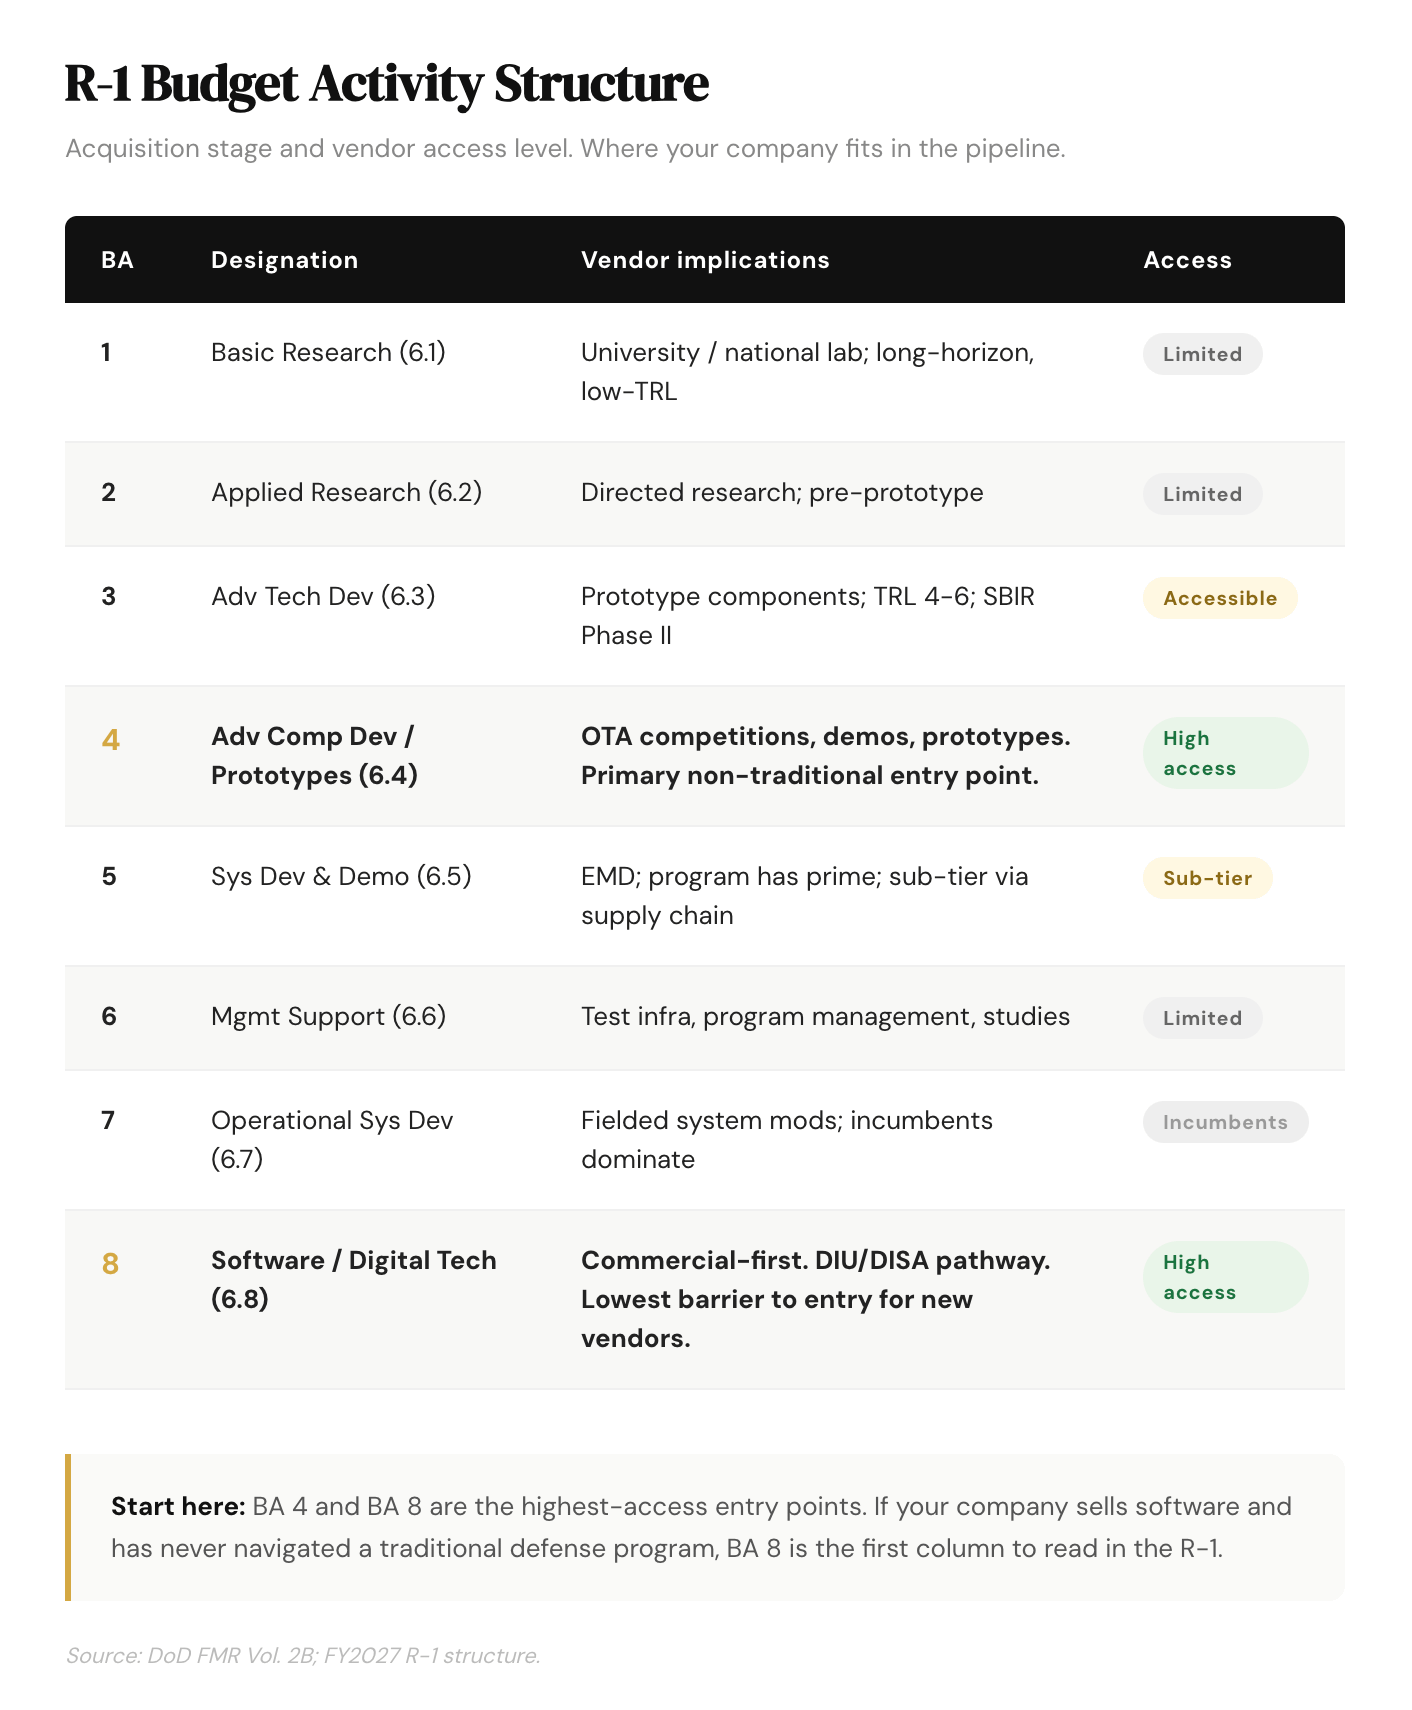
BA 8 deserves a specific note. It was created to give the department a dedicated acquisition pathway for commercial software that does not require a full defense acquisition program. The DISA Software Pilot Program, the Air Force Digital Transformation Office line, and certain DIU-connected lines all live in or adjacent to BA 8. If your company sells software and has never navigated a traditional defense program, BA 8 is the first column you should be reading in the R-1.
WHY NOW
The FY2027 budget books landed in April 2026. The appropriations process is underway. Congress will hold authorization and appropriations hearings, mark up the request, and pass, or continue under a continuing resolution, the FY2027 National Defense Authorization Act and defense appropriations bill. That legislative process typically takes three to nine months. The window between budget submission and enacted law is when BD positioning matters most.
By the time a contract award is announced, the competitive landscape has already been shaped. Teaming agreements form during source selection prep. SBIR topics that align with funded PEs are published before solicitations post. Program offices issue requests for information and sources sought against lines that already have appropriations. All of that pre-solicitation activity flows downstream from the budget books, specifically from the program element numbers that appear in the R-1 today.
A few examples of why the growth trajectories in this specific budget matter right now. Army Artillery Systems EMD (0604854A) jumped from $76.8 million to $709.2 million, an 824% increase. That is not a stable incumbency. That is a program being rebuilt from scratch under a new concept (Mobile Tactical Cannon), and the vendors who understand what the Army is trying to do here, and who have registered against the right NAICS and PSC codes, are the ones who will see the pre-solicitation activity first. Army Future Long Range Assault Aircraft (FLRAA/MV-75) moved from $1.53 billion to $2.14 billion while also accelerating its fielding target to FY2027. Air Force F-47 system development appears in the R-1 at approximately $5 billion, the first year it is visible at that funding level, which means the sub-tier supply chain is still forming.
The budget is the demand signal. The R-1 and P-1 books contain the specific program element numbers that will appear on future SAM.gov solicitations. Reading them now, before the RFPs are issued, is the advantage.
THE FY2027 DEFENSE BUDGET LANDSCAPE
WHERE THE MONEY LIVES
Before reading any program element, you need to understand the architecture. The FY2027 Department of War President’s Budget is not a normal defense budget. It is a $1.5 trillion funding event, $1.1 trillion discretionary plus $350 billion in mandatory reconciliation, the largest single-year defense request since World War II. That context matters for every number in the tables below. When you see a 160% RDT&E increase for the Air Force or a Space Force line that more than doubles, those are not rounding errors. They are structural realignments of national security investment.
The RDT&E exhibit (R-1) is where I start. It shows where the Department is betting on future capability. Every program element number, every budget activity code, and every year-over-year change in the table below is drawn directly from the official FY2027 R-1 document at comptroller.defense.gov.
Data note: All dollar figures in the tables below are drawn from the FY2027 R-1 exhibit (dollars in thousands in source; converted to millions for display). The FY2026 figures represent enacted amounts. FY2027 totals include both discretionary and mandatory (reconciliation) components. The Golden Dome for America Fund is a new standalone appropriation account (3007D) that did not exist in FY2026.
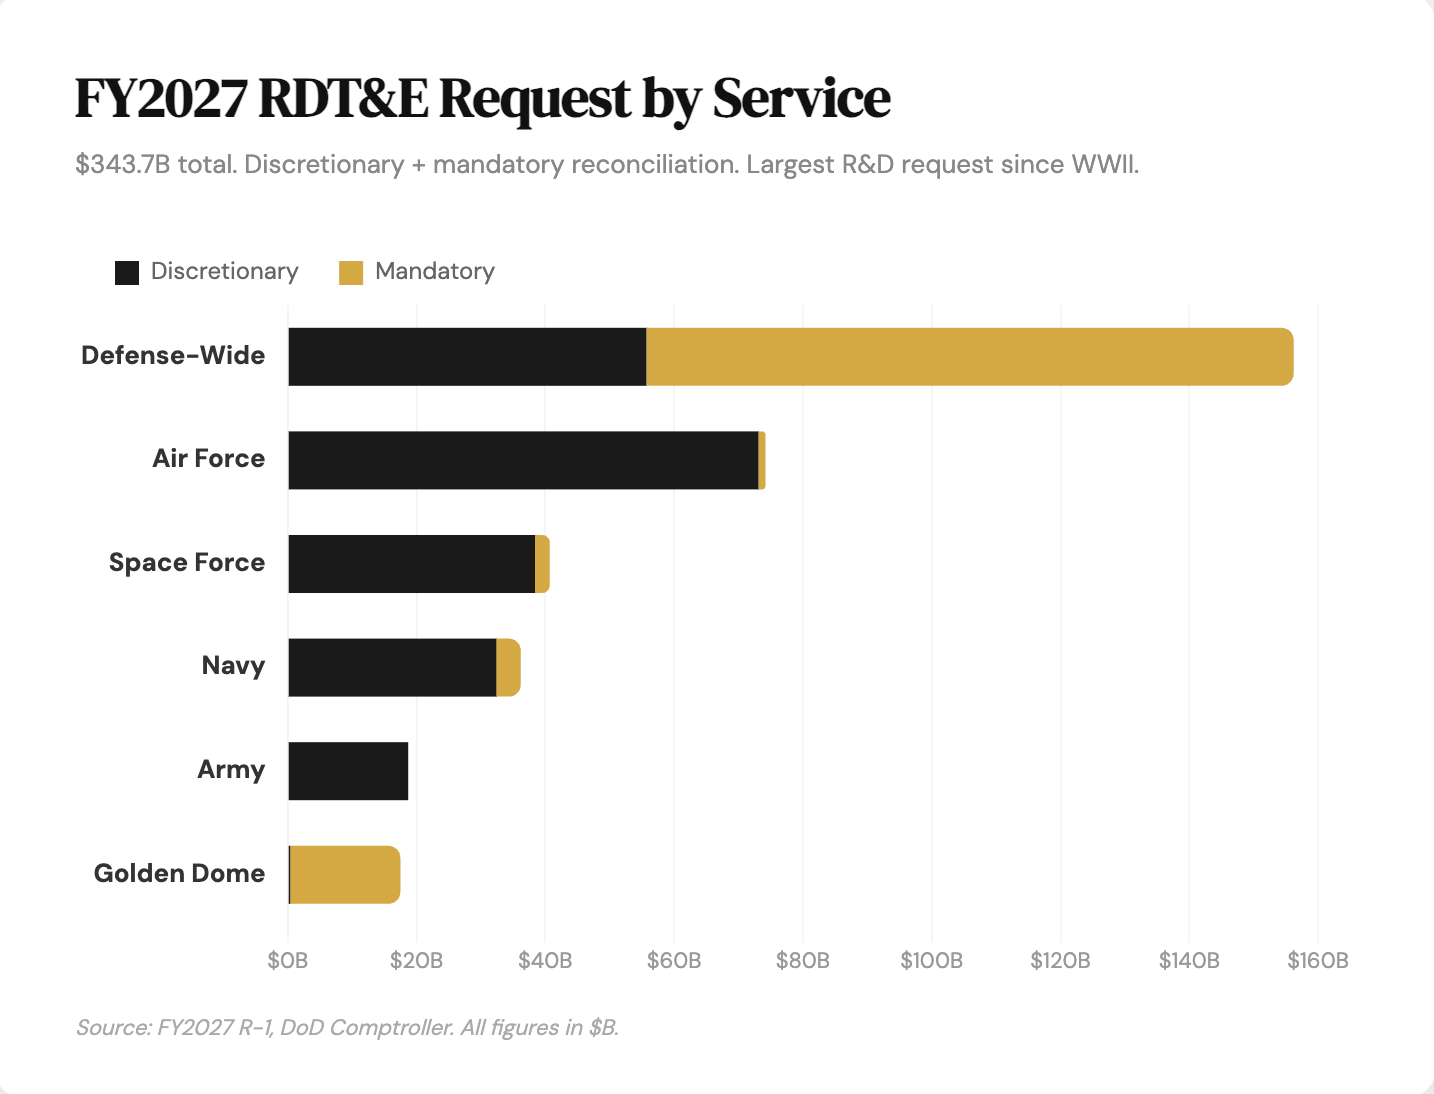
The Air Force jump, from $50.3 billion to $74.2 billion, is the largest absolute dollar increase among the services in discretionary terms. Three programs drive most of it: the F-47 sixth-generation fighter (PE 0207110F, $7.4 billion), the Ground-Based Strategic Deterrent/Sentinel (PE 0605238F, $4.5 billion), and the Collaborative Combat Aircraft (PE 0207147F, $1.4 billion). The Air Force FY2027 discretionary RDT&E alone exceeds the entire DoD RDT&E budget from a decade ago.
Space Force is the real structural shock. $14.8 billion to $40.7 billion, a 175% increase, means Space Force RDT&E in FY2027 now exceeds the entire Space Force budget that existed two years ago. The mandatory component ($2.3 billion) includes Golden Dome architecture elements related to resilient missile warning and tracking. The discretionary component reflects a massive acceleration of Space Force’s role in contested space operations, communications, and next-generation surveillance.
Defense-Wide is the anomaly that needs its own sentence: the $100.5 billion mandatory line inside Defense-Wide RDT&E is almost entirely the reconciliation infrastructure for programs spanning DARPA, MDA, and joint-use technology development. It is not an operating budget. It is a one-time structural investment in the industrial base and capability pipeline.
The O&M exhibit (O-1) tells a different story than R&D. Operations and maintenance is the budget that keeps the force running, people, readiness, infrastructure, and the back-end of every system that procurement and R&D put into the field. The FY2027 O&M request is roughly $430 billion total (discretionary plus mandatory), with the mandatory component capturing everything from military healthcare to environmental remediation.
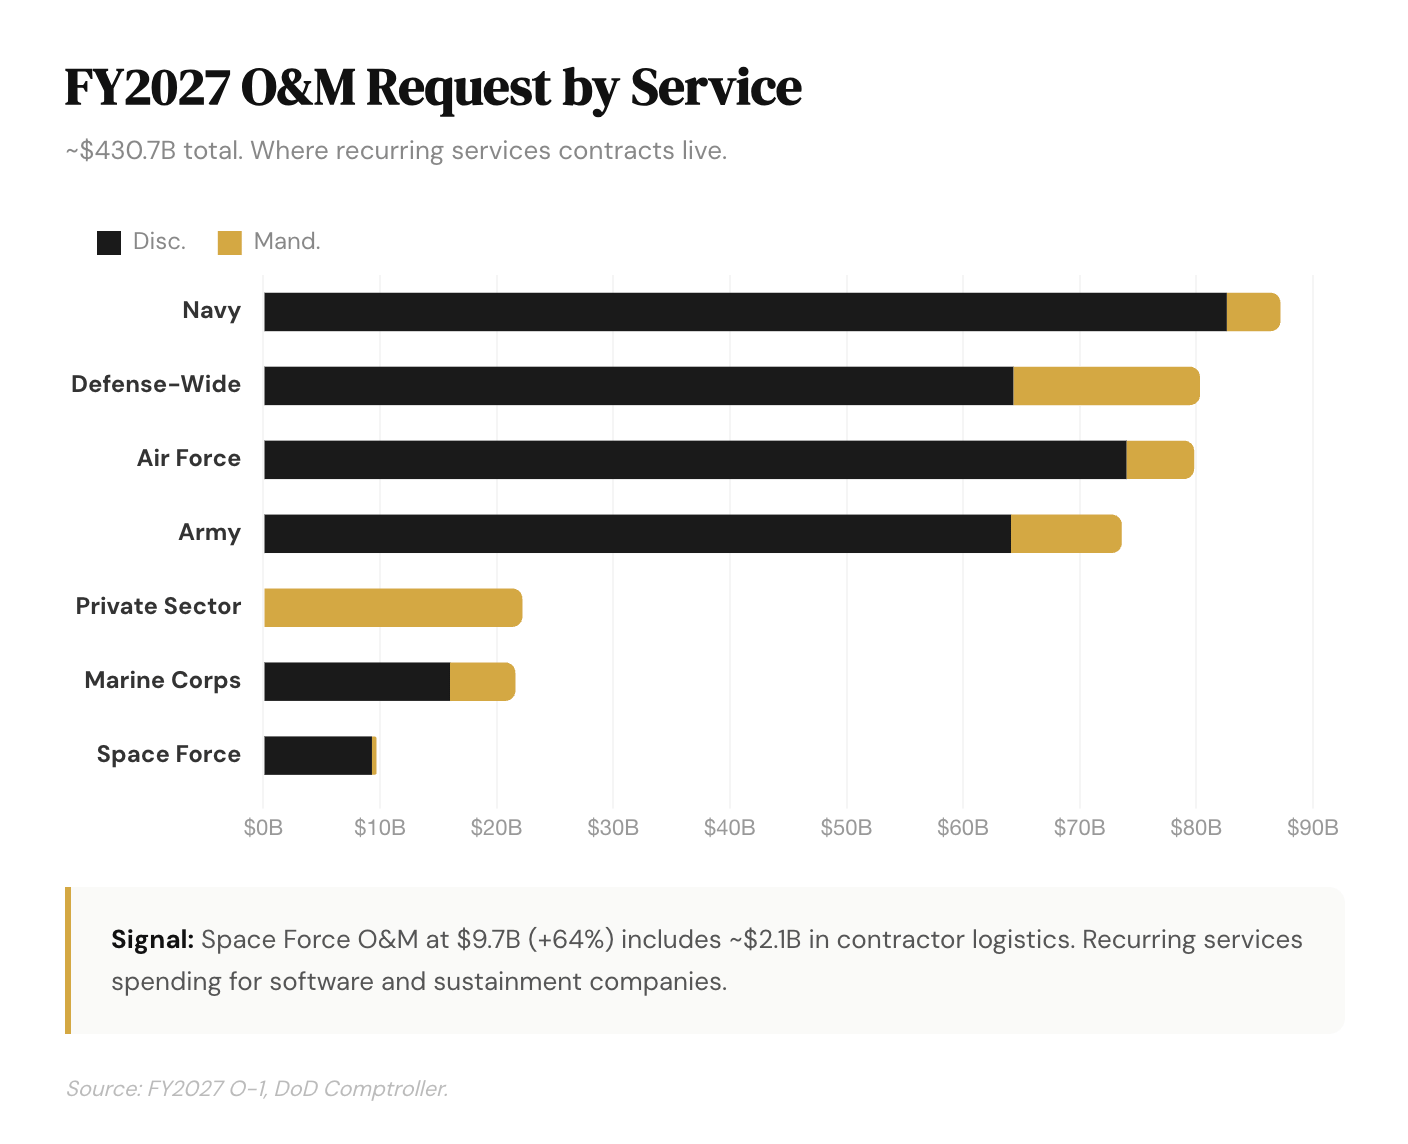
Space Force O&M at $9.7 billion is notable: this is a force of approximately 10,000 Guardians sustaining infrastructure worth multiples of that number. The per-Guardian O&M investment reflects both the complexity of the systems Space Force operates and the rapid expansion of its command and control architecture. Defense-Wide O&M at $80.2 billion is where DISA infrastructure, SOCOM operations, and the joint enabling commands live.
The signal here: The Golden Dome fund structure tells you something important that the headline number obscures. The $17.5 billion in 3007D is not MDA’s budget. It is a cross-agency investment vehicle with six executing agents. That means six separate acquisition strategies, six separate program offices, and six separate entry points for industry. DARPA’s $174 million inside Golden Dome is specifically targeting disruptive concepts that existing programs have not attempted. SCO’s $200 million is rapid prototyping authority. If you are a non-traditional vendor with a novel kill-chain concept, those two lines are more accessible than the MDA main account.

READING THE SIGNALS
WHAT THE FY2027 NUMBERS ARE ACTUALLY TELLING YOU
Budget numbers are not marketing. They are allocation decisions made by people who have already decided what they think the next war looks like and what capabilities they believe will be needed to fight it. My job, and yours, is to read those decisions accurately before the rest of the market does.
The table below maps the most significant program element signals in the FY2027 R-1. I selected these lines based on three criteria: absolute dollar magnitude, year-over-year percentage change, and strategic alignment with the Department’s stated priorities.
Data note: All FY2026 figures are enacted amounts. FY2027 figures are the President’s Budget request; they are not law. Programs marked “NEW” did not have a standalone line in FY2026.
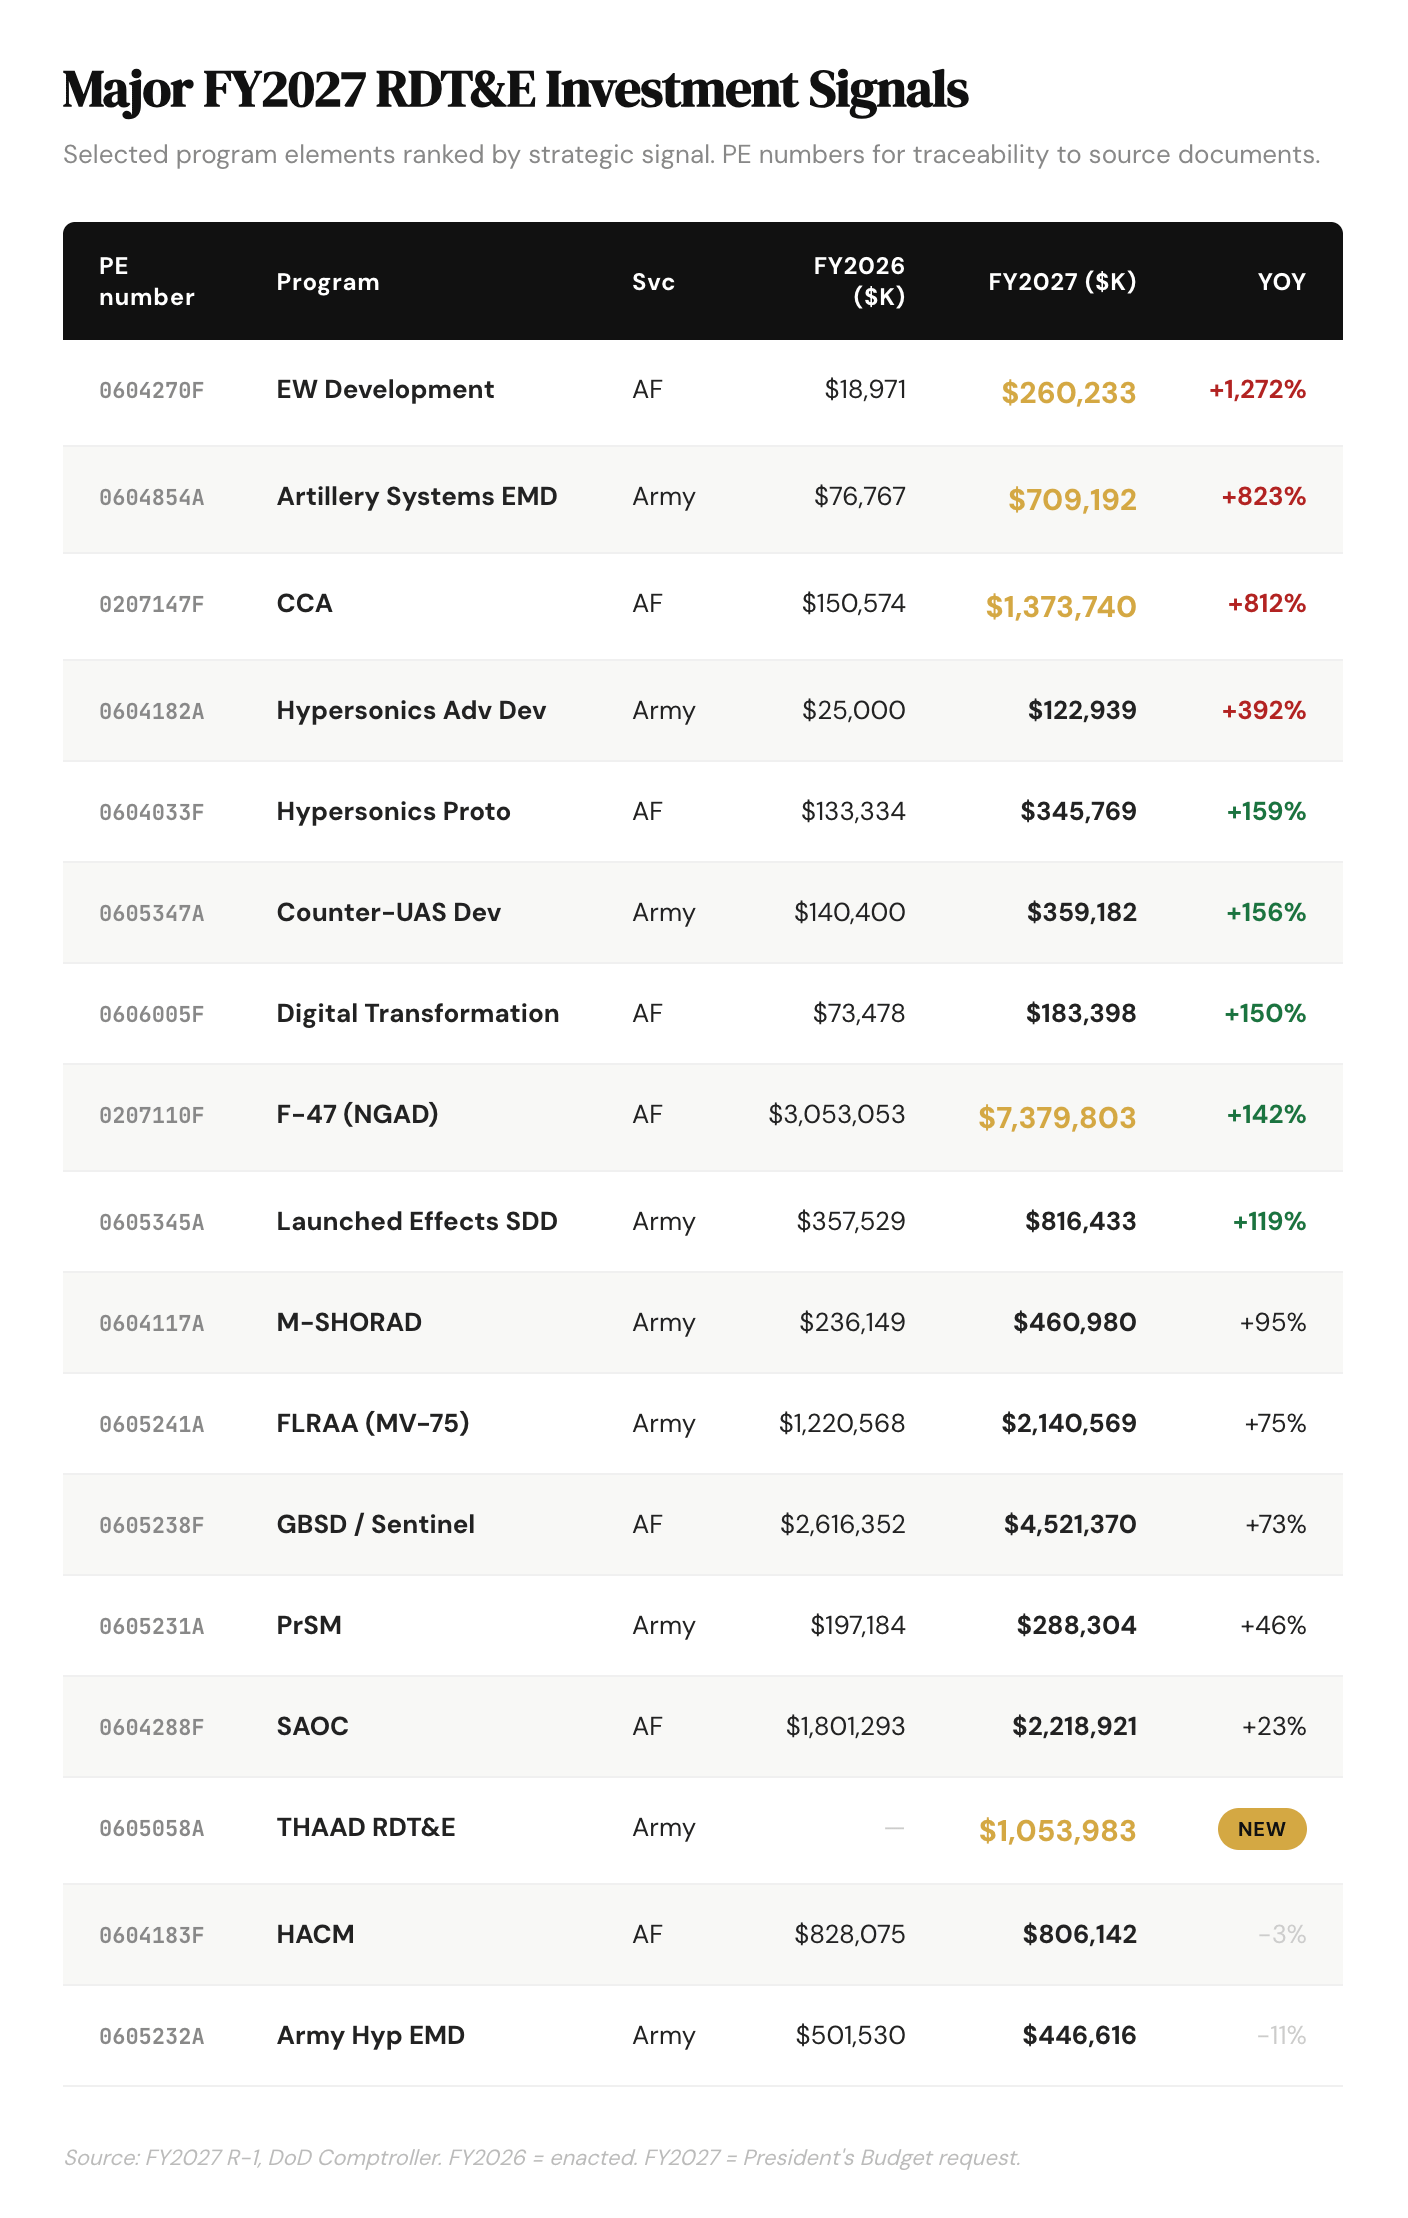
The single most important signal in the entire FY2027 budget is not the F-47, and it is not Golden Dome. It is Artillery Systems EMD at $709 million (PE 0604854A), a +823% increase off a $76.7 million base.
Here is why. The Army killed the XM1299 Extended Range Cannon Artillery program in 2024 after years of barrel wear failures, schedule slippage, and cost overruns. That program was developed by BAE Systems on an M109A7 chassis. The Army is now funding a completely new engineering, manufacturing and development program under the Mobile Tactical Cannon banner, and they are putting $709 million into it in a single year. That is not incremental R&D. That is a full EMD funding profile for a new artillery system. The prime competition has not been publicly awarded. No contractor has a locked position. That is an open market.
The EW Development jump, PE 0604270F, from $19 million to $260 million(+1,272%), is the second most important signal that almost nobody is tracking. The Air Force does not grow an EW development line by 13x in one year unless they have already identified capability gaps that existing programs are not addressing. This is a pre-competitive signal. The solicitation for whatever this money funds has not posted yet. Firms with coherent electronic warfare system architecture, RF sensing, jamming, directed energy, or integrated EW, should be building their understanding of this line now.
The CCA number confirms what the production decision timeline already implied. +812% for PE 0207147F means the Air Force has moved from a prototype-cost model to a production-cost model. Anduril’s Arsenal-1 factory in Ohio went operational in March 2026 with a 150-aircraft-per-year capacity. General Atomics is completing ground testing on the YFQ-42A. The production decision is expected by September 2026. This is not a research program anymore.
The two decreases deserve brief comment. HACM (PE 0604183F, -3%) is not a program in trouble. It is a program reaching the end of its development investment cycle, transitioning toward IOC. Army Hypersonics EMD (PE 0605232A, -11%) reflects a rebalancing of the Army hypersonics portfolio as the CPS/Dark Eagle program transitions to production activity under Lockheed Martin Space.
What follows is a six-stage process. It moves from market research through capability alignment, solicitation monitoring, teaming strategy, compliance readiness, and pipeline construction. Each stage builds on the one before it.
You do not need to enter at Stage 1. Most companies are already somewhere in this sequence. The value is knowing exactly where you stand and what the next move is.
MARKET RESEARCH
WHO ALREADY OWNS THIS SPACE?
Before you write a single line of a capability brief, before you identify a teaming partner, before you decide which program office to engage, you need to map who already has prime contract relationships in the specific program areas the budget is funding. This is not due diligence. It is survival. The BD teams at Boeing, Lockheed Martin, Anduril, and RTX have been working these accounts for years. If you do not understand what they own, you will write proposals that compete with them on their home turf and lose. If you do understand what they own, you can find the seams.
I run market research in three parallel tracks: prime award history via USAspending.gov, active vehicle holders via SAM.gov IDIQ databases, and open-source program reporting from defense media. The table below maps the contracting office, prime, contract vehicle, and sub-tier entry path for each major FY2027 program area.
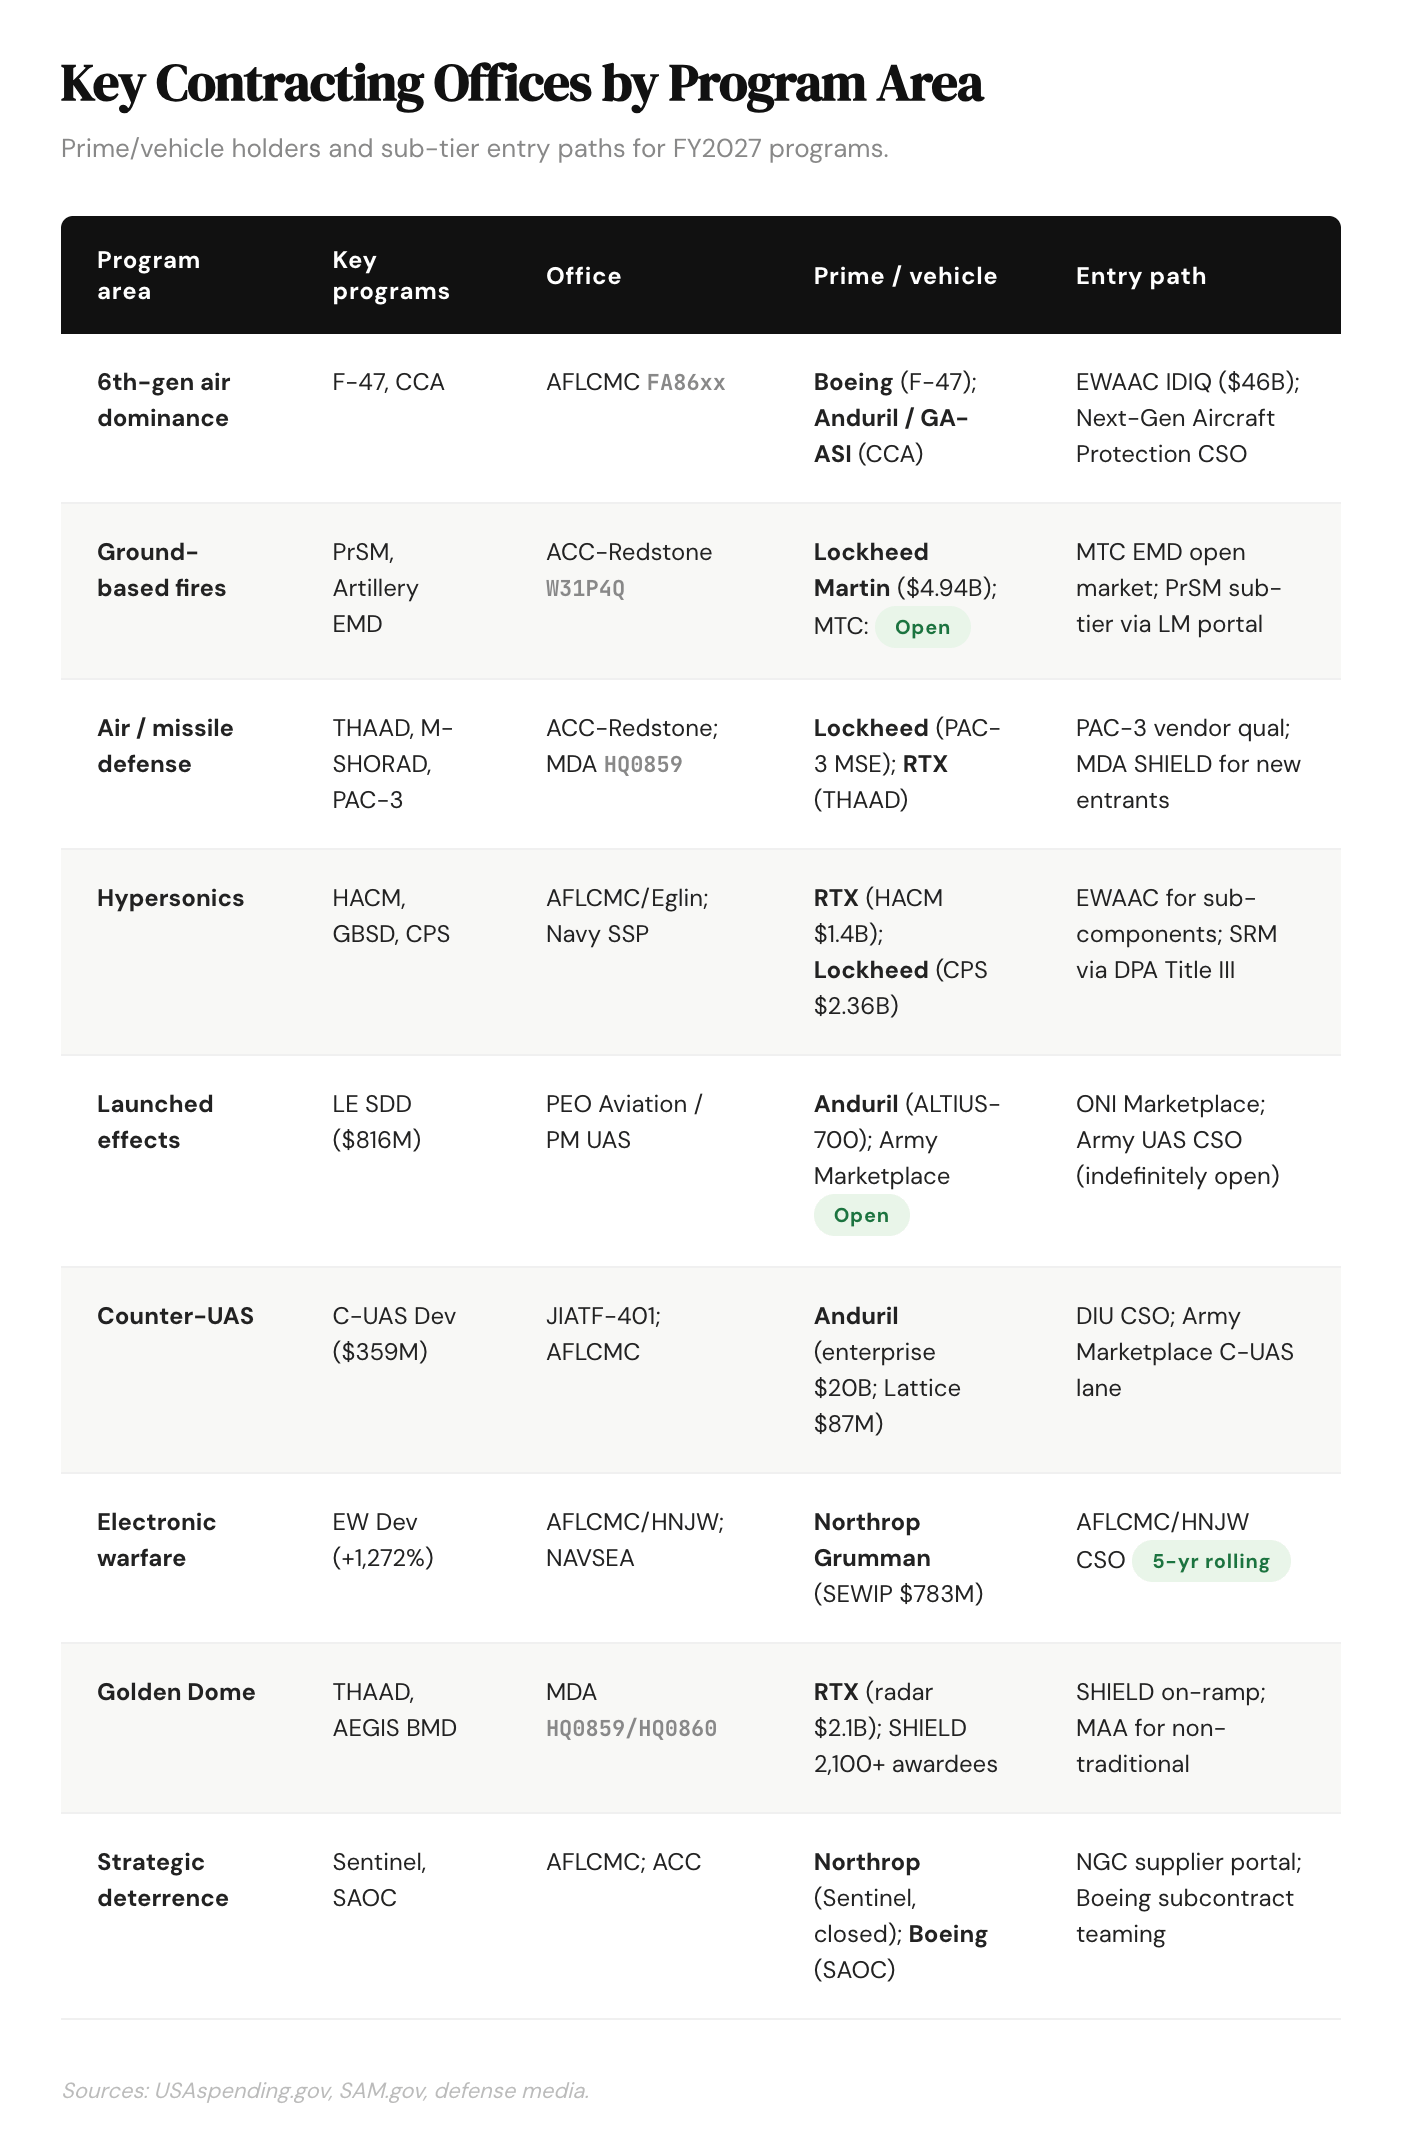
The USAspending data reveals a consistent pattern across the high-growth program areas: most large prime awards in FY2025-2026 were either sole-sourced or restricted to incumbents. Boeing holds the F-47 on a cost-plus incentive fee structure awarded March 21, 2025. Lockheed Martin holds PrSM on a $4.94 billion IDIQ sole-source, also awarded March 2025. RTX holds HACM through MTA authority that pre-dates normal competition requirements. None of those seats are available to new entrants at the prime level in the near term.
But the Artillery Systems EMD program is different. The Mobile Tactical Cannon has not been awarded. The $709 million FY2027 EMD investment is going into a competition that has no identified prime as of this writing. That is the most significant open market for a new prime position in the FY2027 Army fires portfolio.
The signal here: The AFLCMC/HNJW Two-Step CSO for Next-Generation Aircraft Protection Technologies is the most important open solicitation that BD teams at EW-capable companies are currently underweighting. It has a five-year rolling call structure, four Areas of Interest (sensing, processing, defeat layer, and system architecture), and it feeds directly into the survivability architecture for both the F-47 and CCA. The $260 million EW development line (PE 0604270F, +1,272%) funds the demand that this CSO will fulfill. Most small EW firms I track are not registered on this vehicle.
Why This Matters
Market research in defense is time-constrained. By the time a solicitation posts on SAM.gov, the prime has usually already selected its sub-tier team and the government has already drafted its source selection criteria around the capabilities of firms they already know. That pattern is consistent across nearly every program in the FY2027 budget. The Boeing F-47 sub-tier decisions are being made now, not at RFP release. Anduril’s supply chain for the YFQ-44A is being assembled now, before the production decision is formalized. If you are doing market research after a solicitation posts, you are doing it too late.
Identifying the open competitions early gives you a positioning window measured in months, not weeks. That is the difference between being on the source selection committee’s radar before evaluation and arriving cold.
How to Apply It
Pull every contract award in NAICS codes 336411 (aircraft), 336419 (missiles), 334511 (EW/sensors), and 541715 (R&D services) from USAspending.gov for the 24 months ending April 2026, filtered to AFLCMC, ACC-Redstone, and MDA as awarding offices. Cross-reference the PE numbers from the Signal Table against the product/service code and description fields. This gives you the current prime holder map for every major FY2027 R&D line.
For the three open competitions identified in this section (Artillery Systems EMD, Air Force EW Development, Golden Dome SHIELD on-ramps), build a pre-RFP engagement plan: identify the program manager name at the relevant PEO and request an industry day or capability briefing before the draft RFP releases. The government is required to conduct market research; your briefing is data for their acquisition strategy.
For every program where a prime is already locked (F-47, CCA, PrSM, PAC-3 MSE), map the prime’s known sub-tier gaps rather than competing at the prime level. Register on all four prime supplier portals (Boeing Supplier Portal, Lockheed Martin Exostar, RTX SupplyOn, Anduril supplier intake) and submit a capability statement before the prime’s sub-tier selection decisions close.
CAPABILITY ALIGNMENT
DOES WHAT YOU DO MATCH WHAT THE BUDGET ACTUALLY FUNDS?
Most companies describe their capabilities in terms of what they are proud of building. The government buys capabilities in terms of what problems it is trying to solve. Those two framings are not the same, and the gap between them is where most BD efforts fail.
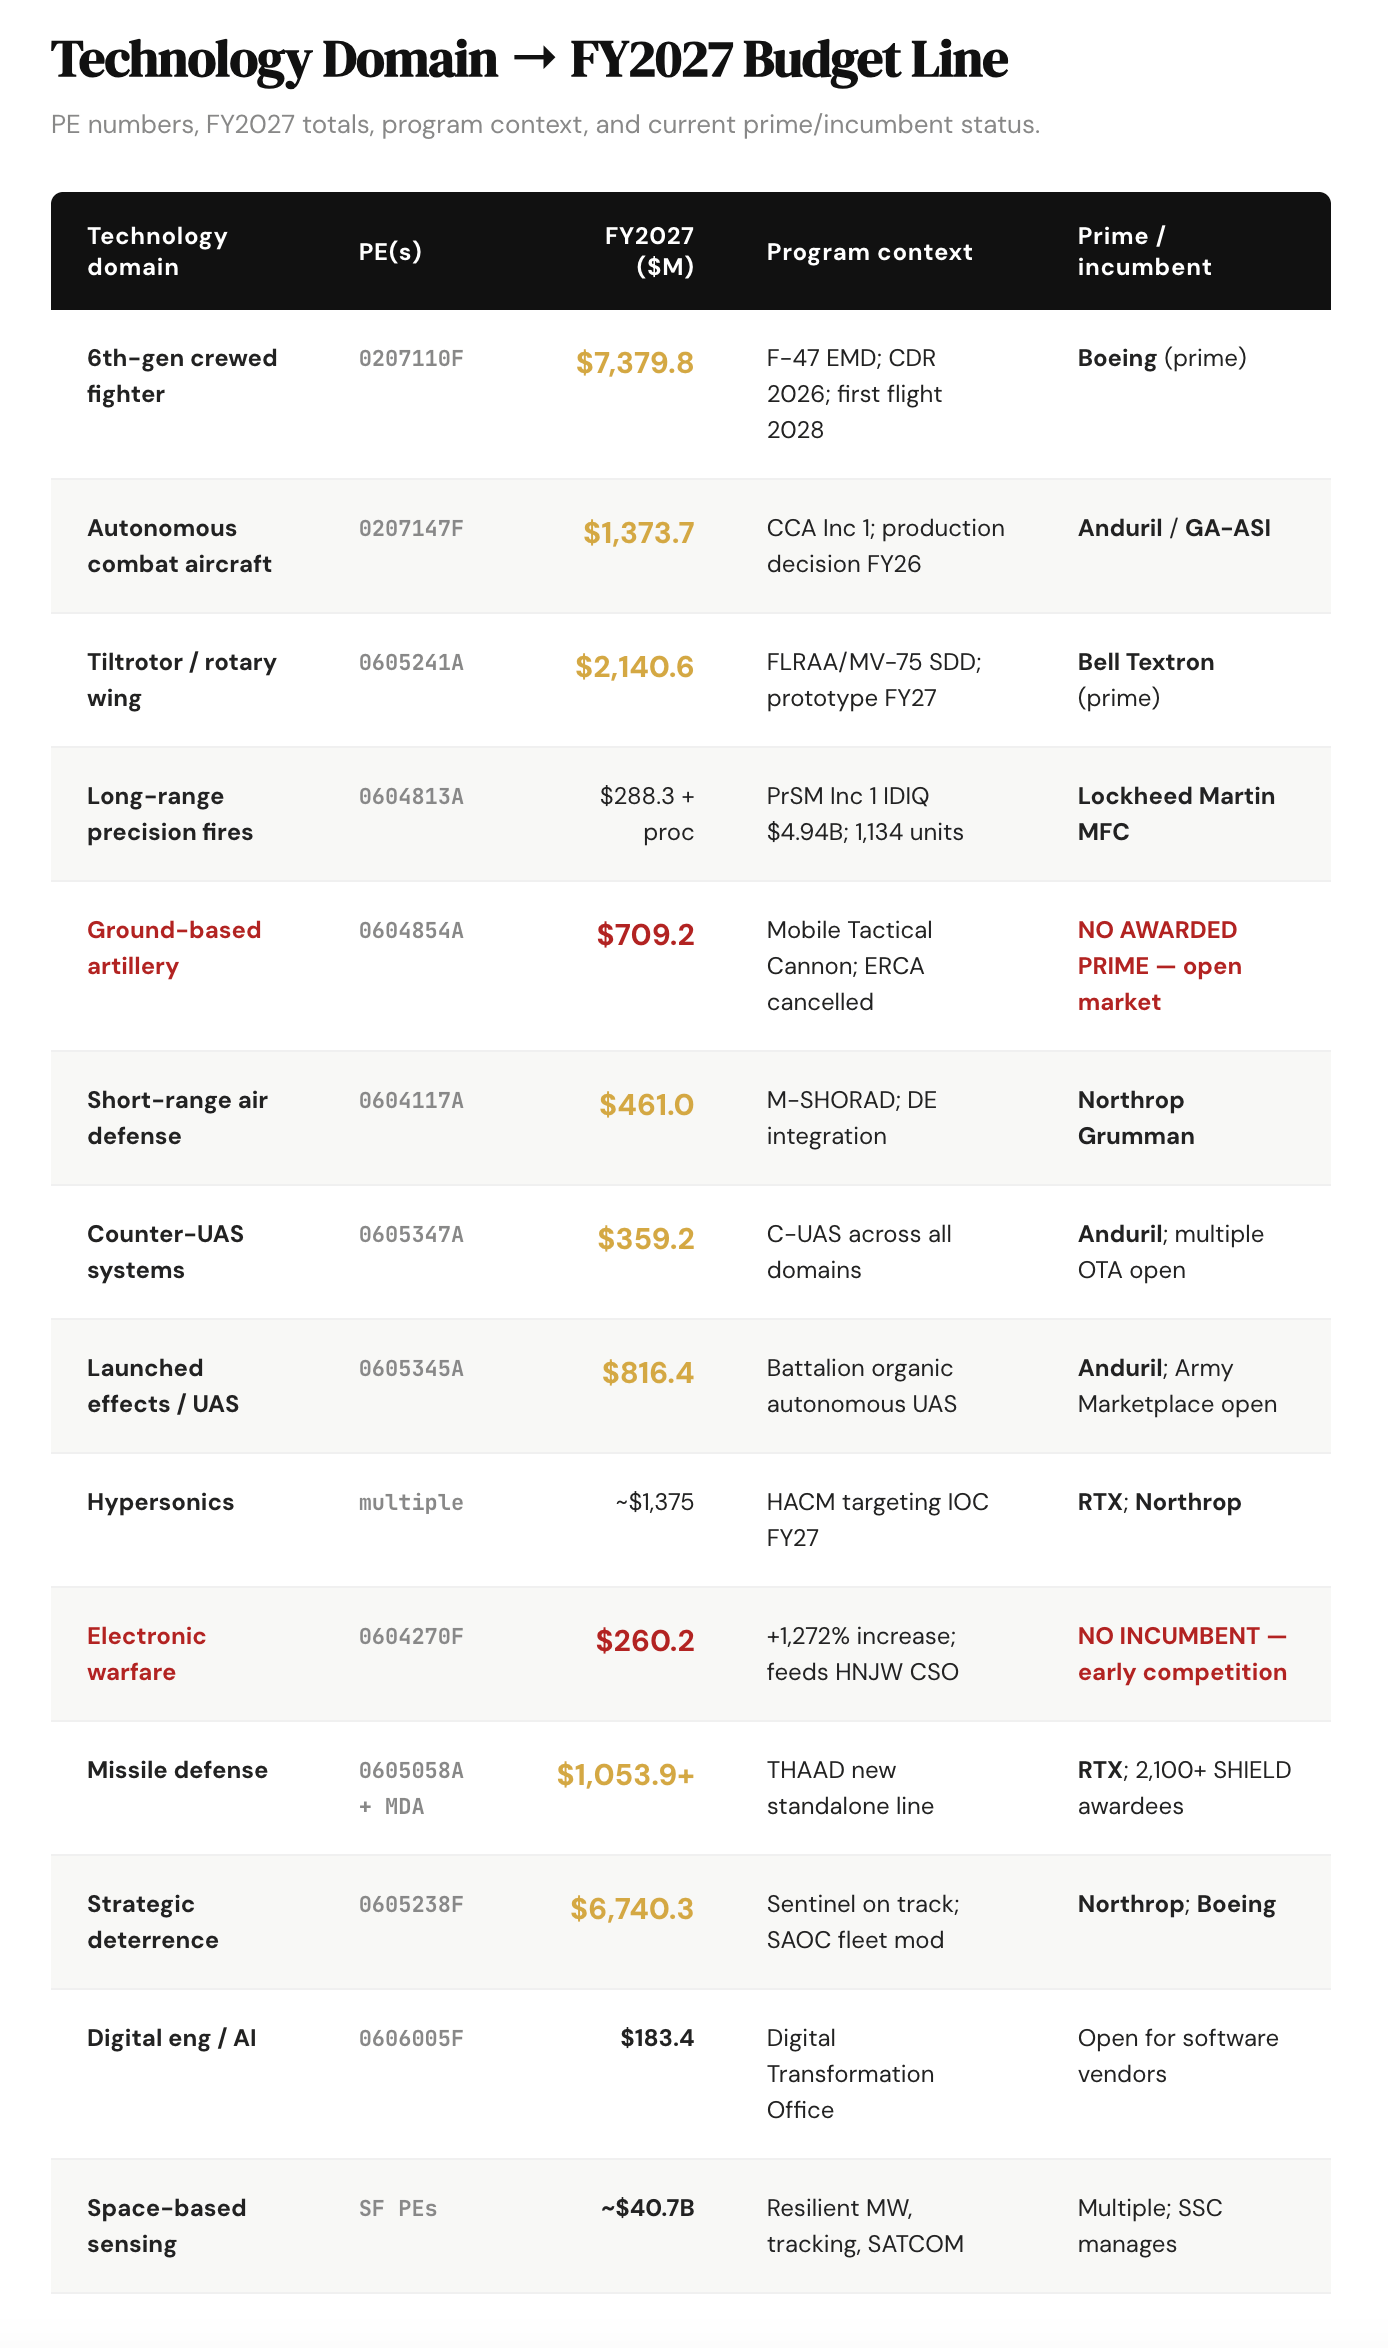
Capability alignment is the discipline of translating your technical capabilities into the specific budget lines, PE numbers, and program requirements that the government has actually funded. The question is not “can we do this?” It is “does what we do match what PE 0604270F funds, and can we prove it with performance data?” If you cannot answer the second question, you will not survive source selection regardless of how good your technology is.
The table below maps technology domains to their corresponding FY2027 budget lines. This is the translation layer between your capabilities and the market.
From Budget Lines to Entry Points
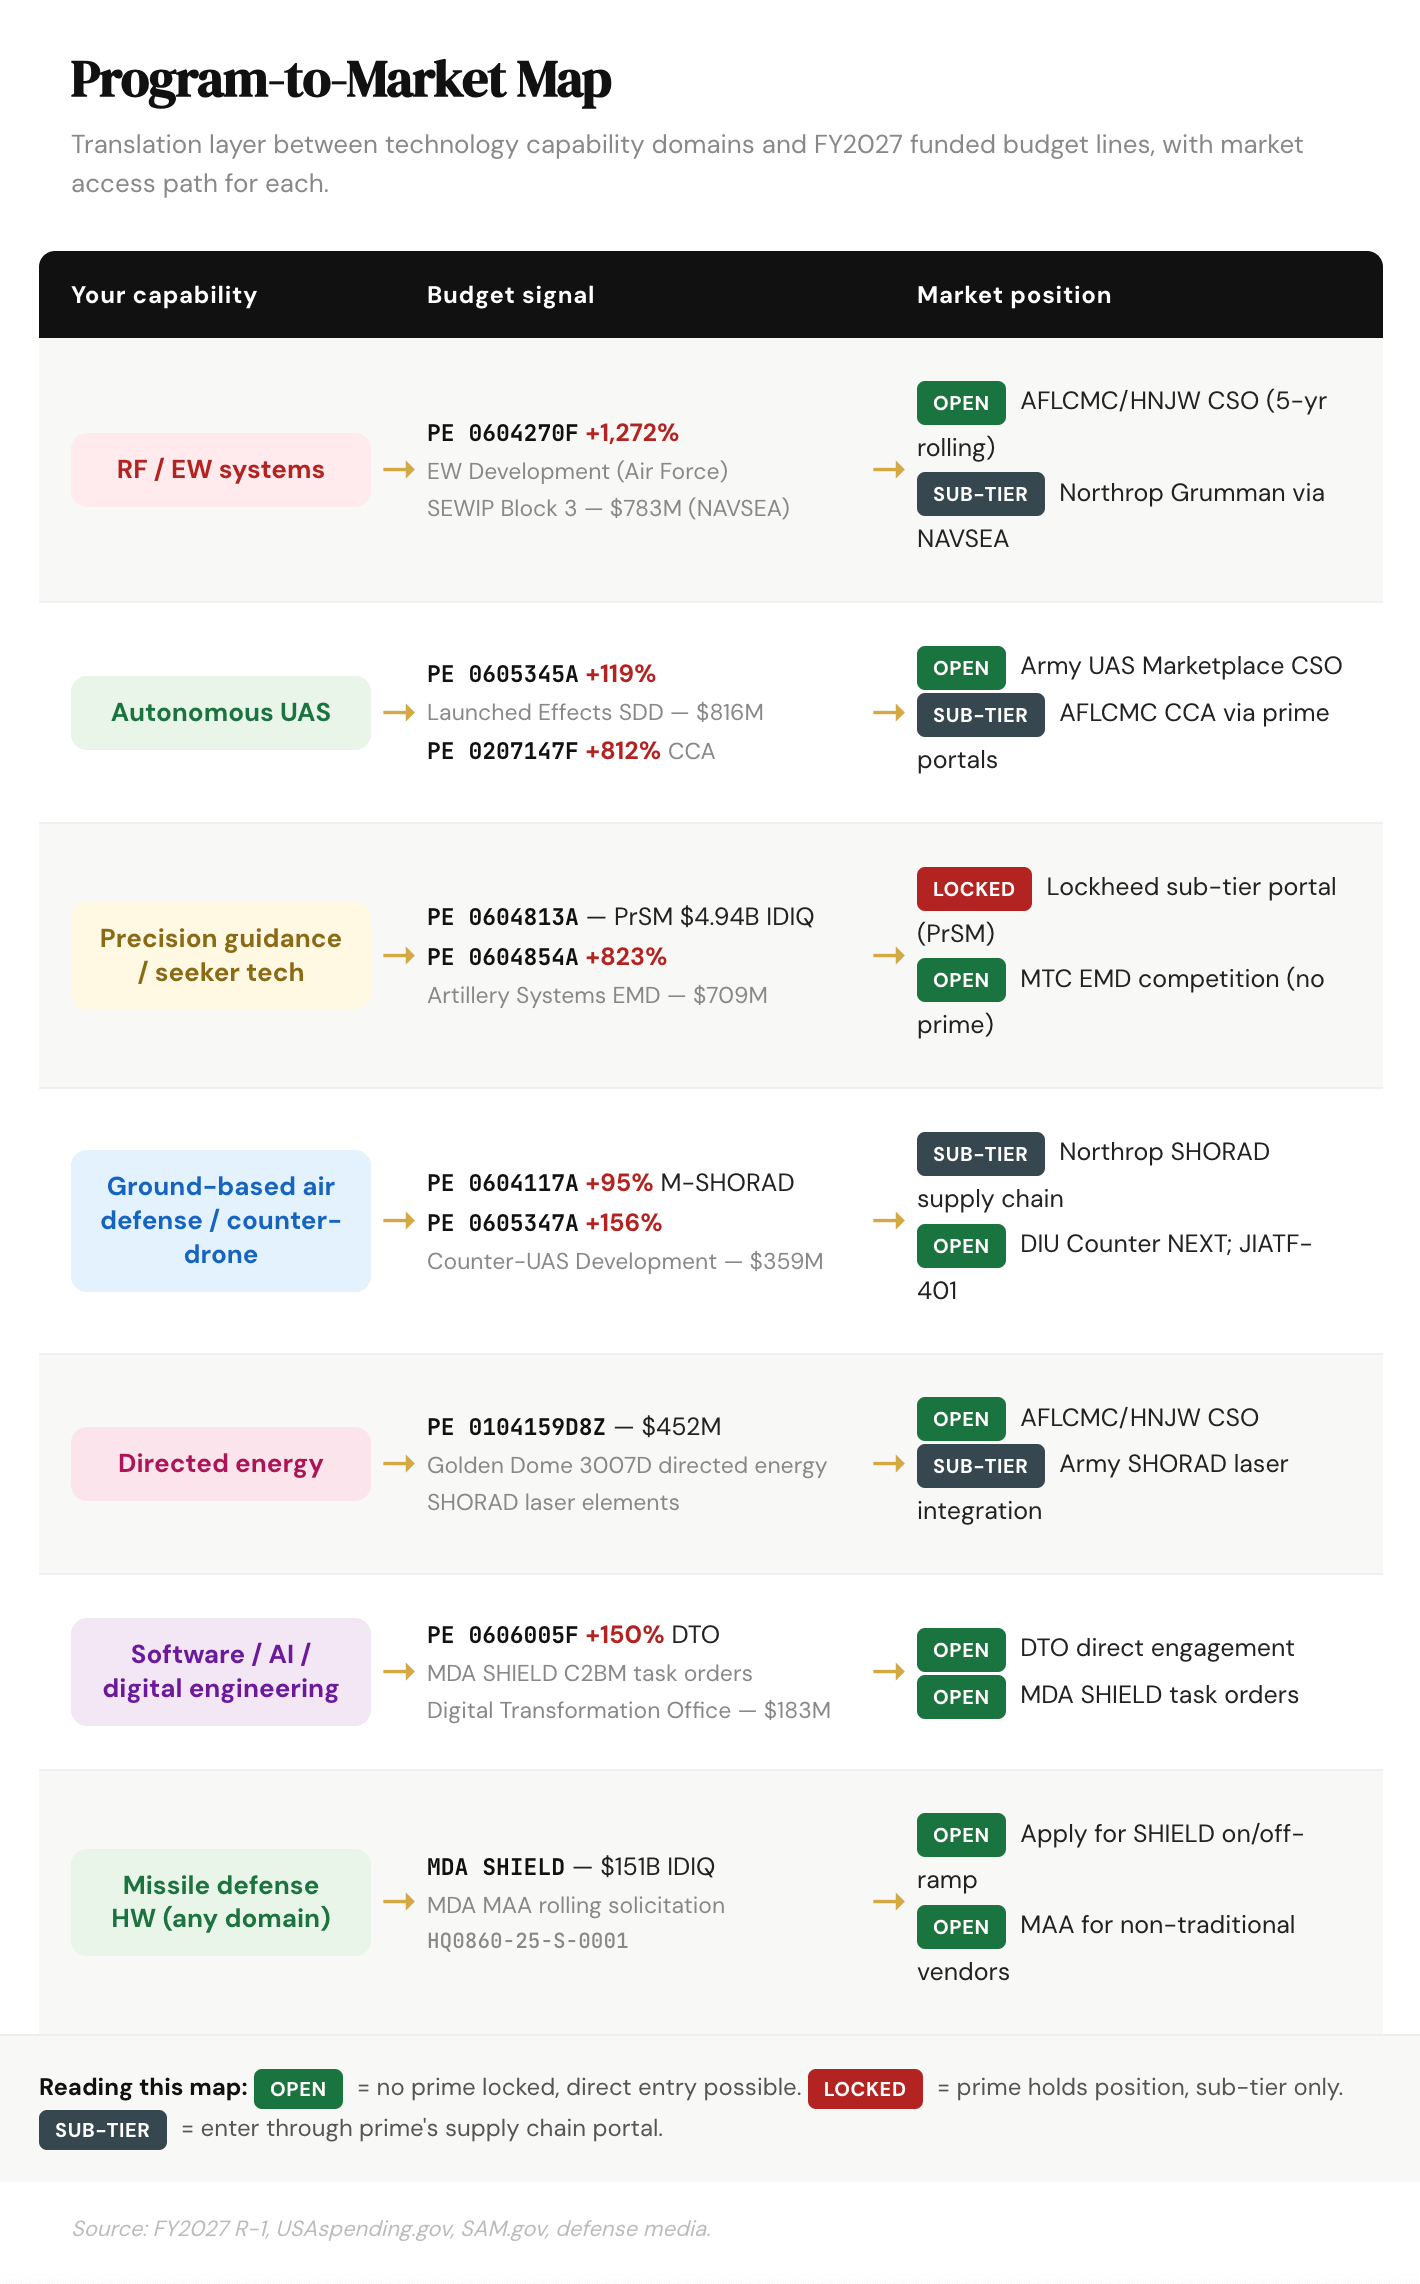
The table above gives you the data. The map below gives you the action. It connects your capability domain to the specific PE that funds it, then to the contract vehicle or market position where you can actually enter. Programs marked OPEN have no locked prime. That is where new positions get established.
Why This Matters
The FY2027 budget contains three categories of market position: locked, competitive, and open. Locked means a prime has an existing contract with options, a sole-source justification, or a long-term relationship that effectively forecloses competition at the prime level. Competitive means the program is in a multi-vendor prototype or downselect phase where new entrants can still influence the outcome. Open means the government has funded a program but has not yet established an acquisition strategy or identified a prime.
As of April 2026, the Artillery Systems EMD ($709 million), the Air Force EW Development line ($260 million), and the THAAD RDT&E standalone line ($1.054 billion) are all in the “open” or “early competitive” category. Those three lines together represent $2.0 billion in FY2027 RDT&E where a new prime position can still be established. That window closes the moment the government issues a draft RFP.
How to Apply It
Map your three strongest technical capabilities against the PE numbers in the table above. For each match, identify whether the market position is locked, competitive, or open using the prime/incumbent column. If every match is locked, you are pursuing sub-tier positioning; if any match is open or competitive, you are pursuing a prime position. The distinction determines your entire BD strategy and timeline.
For programs in the “open” or “early competitive” category (Artillery Systems EMD, AF EW Development, MDA SHIELD task orders), prepare a white paper or capability brief that maps your technology directly to the specific funded capability in the R-1 program element description. Program offices for these lines are conducting market research right now. A two-page capability brief submitted to the relevant program manager six months before RFP release is worth more than a 50-page proposal submitted after it posts.
If your capability maps to a locked program, identify the sub-tier gap rather than the prime position. Use the program’s Bill of Materials logic: what does the prime need that it currently buys from a single qualified source? Solid rocket motor casings, advanced seeker assemblies, precision timers, and RF apertures are all single-source constrained in multiple FY2027 programs.
SOLICITATION MONITORING
WHAT’S ACTUALLY ON THE MARKET RIGHT NOW
Budget signals tell you where money is going. Solicitation monitoring tells you whether the money has turned into an actionable opportunity. Those are two different things on two different timelines. The R-1 tells you what is funded. SAM.gov tells you what is buyable. Between those two data points there is typically a 6-18 month gap, and that gap is where your positioning work happens.
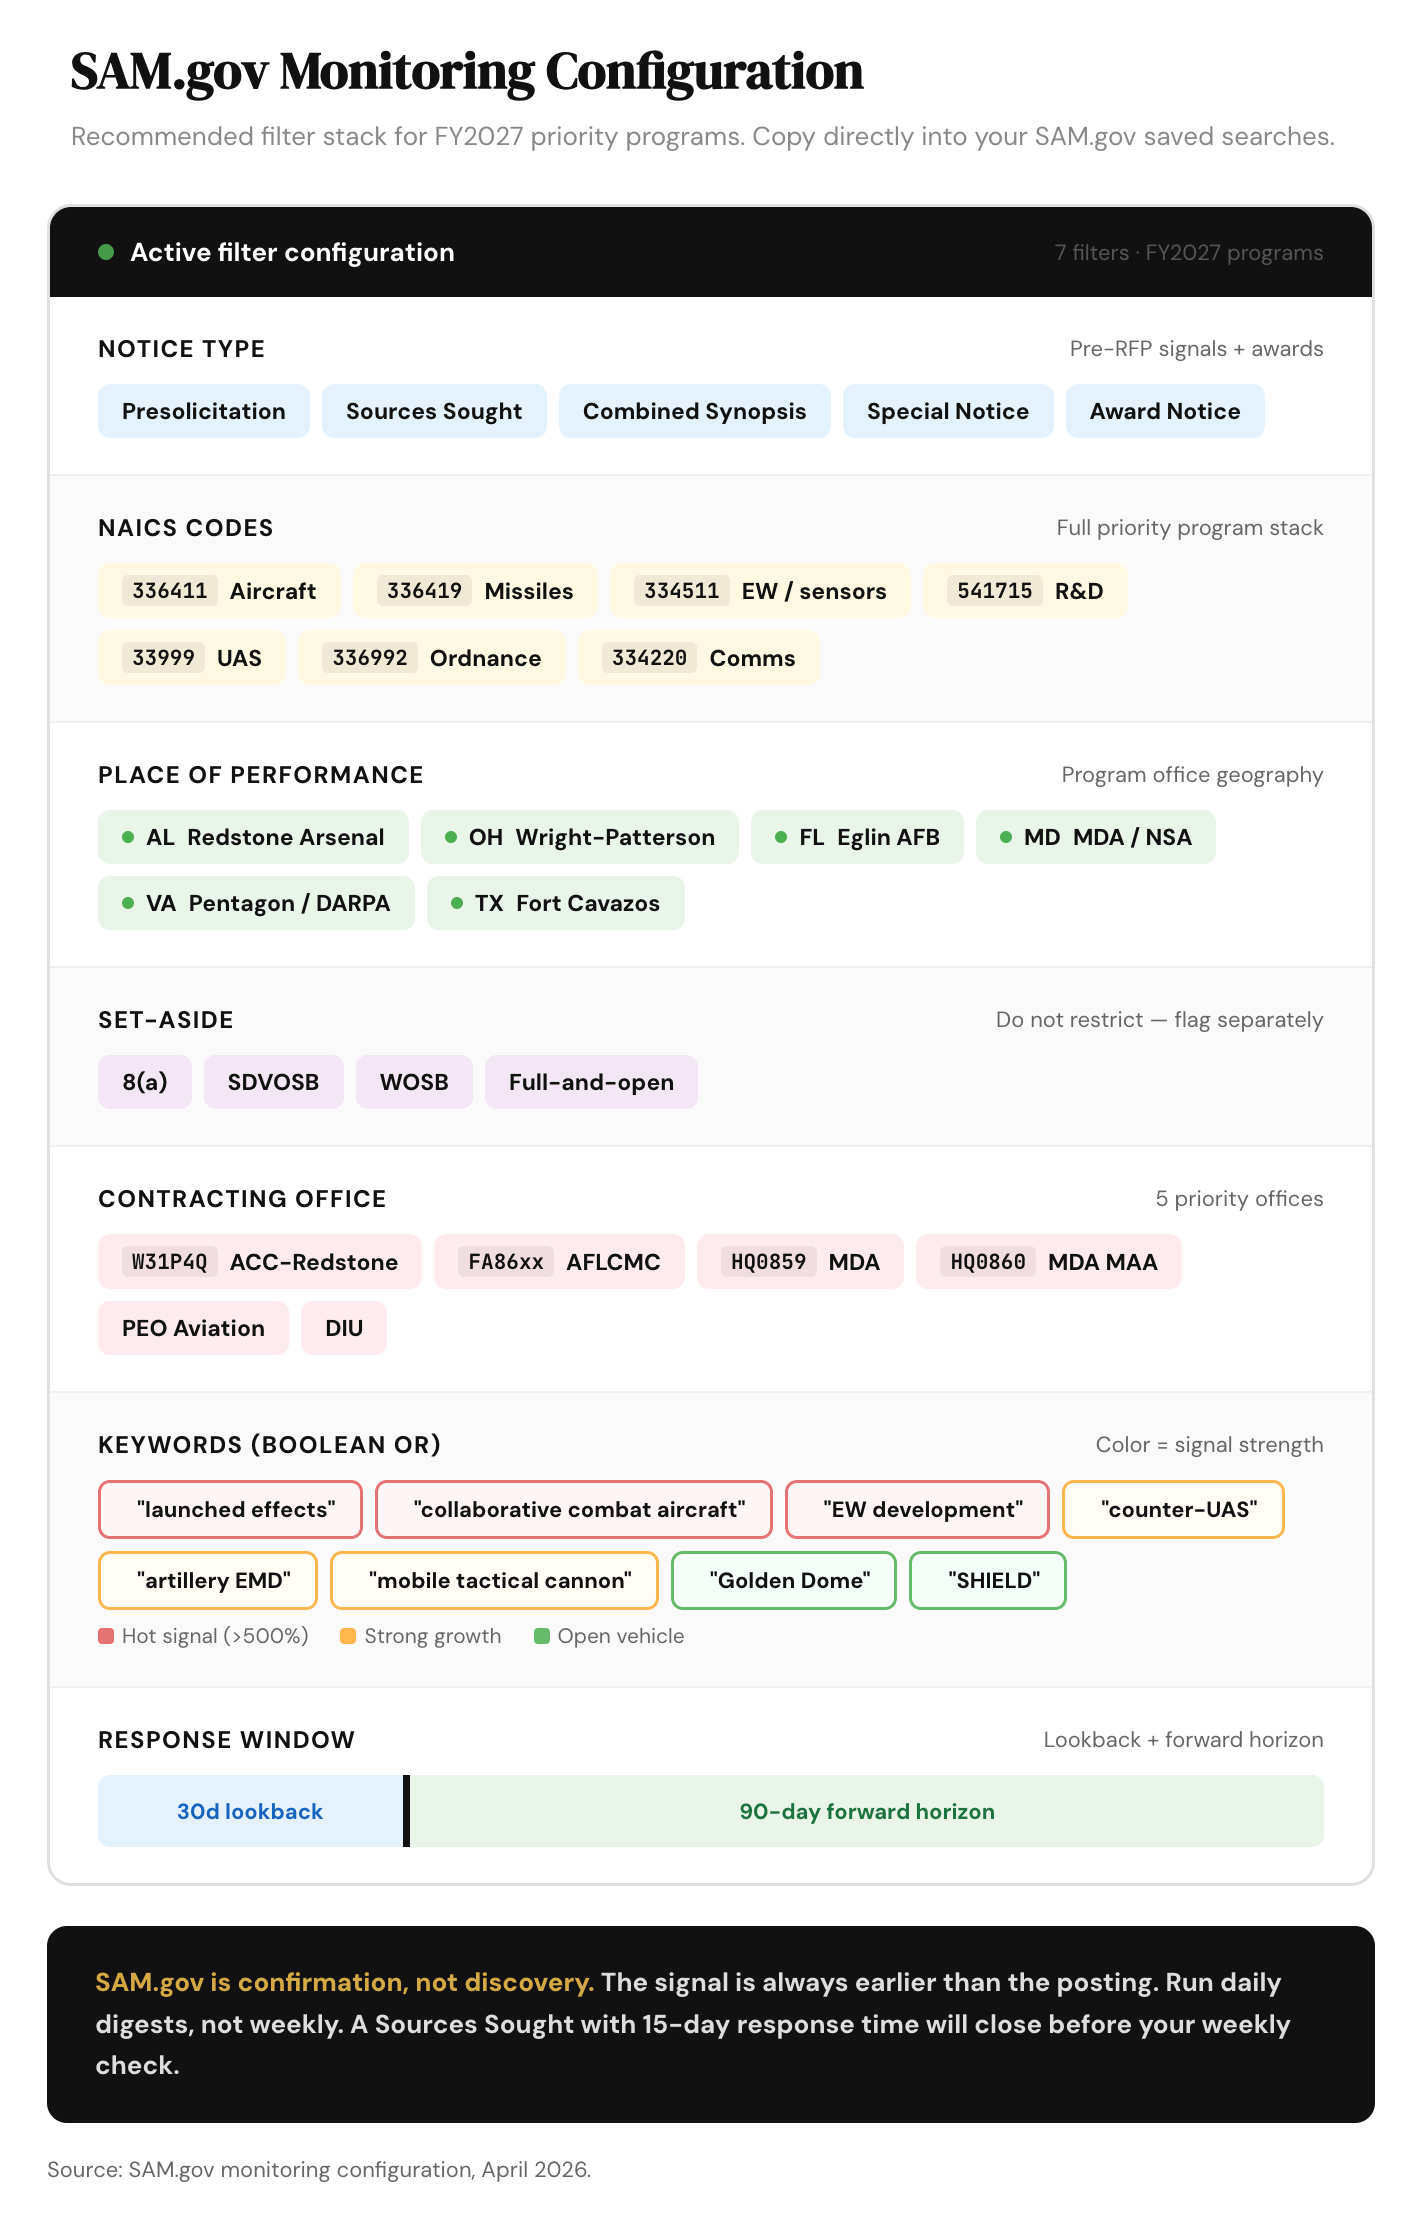
Here are a few examples of what I’ve identified as live, active, or recently active as of April 2026:
MDA Multiple Authority Announcement (HQ0860-25-S-0001): Rolling through March 2030. Targets specifically non-traditional vendors with disruptive technology. Four areas of interest: kinetic/hypersonic defense, C2BM architecture, non-kinetic/EW approaches, and space-based capabilities. This is the entry point for companies that have a viable missile defense technology but do not fit the traditional defense contractor profile. Currently active.
AFLCMC/HNJW Next-Generation Aircraft Protection Technologies CSO: A Two-Step Closed CSO with a five-year open rolling call period. Four Areas of Interest: System Architecture, Detect Layer (sensing), Decide Layer (processing), and Defeat Layer (countermeasures). Feeds directly into F-47 and CCA survivability architecture. Requires a NIST/SPRS assessment due to CUI-protected attachments.
Army UAS Marketplace CSO (PEO Aviation / PM UAS / ACC-Redstone): Indefinitely open as of March 2026. Covers the full UAS ecosystem: platforms, payloads, autonomy software, EW sensors, communications, and ISR. FAR and OT authority. Fastest path for UAS-adjacent technology to reach Army acquisition officers.
Why This Matters
The solicitation monitoring database is not a passive list. It is a lead-time instrument. The earliest signal in the sequence, a Sources Sought notice, typically precedes an RFP by 6-12 months. By the time a Combined Synopsis/Solicitation posts, the program office has usually completed market research, drafted evaluation criteria, and informally communicated with incumbent firms.
The SHIELD on-ramp and the MDA MAA are structurally open in a way that most IDIQ vehicles are not. The window for positioning is now, not in six months when the first SHIELD task order RFPs post.
How to Apply It
Set up automated SAM.gov alerts using the keyword and contracting office filter stack above. Run a daily digest to your BD inbox, not a weekly one. A Sources Sought notice for the Artillery Systems EMD competition will post with 15-30 days response time. If you are checking SAM.gov weekly, you may miss the response window entirely.
If you are not currently on SHIELD, the MDA SHIELD IDIQ on-ramp is your first action item. Pull the Phase 2 on-ramp announcement from SAM.gov, review the technical evaluation criteria, and prepare a capability package that maps your technology to at least two of the four SHIELD mission areas.
For the DIU OMEN CSO, the April 15, 2026 deadline is a hard drop-dead. If your company builds avionics software, tactical data integration, or mission systems for airlift/tanker aircraft, submit a white paper before that date. DIU OT prototype awards do not require recompetition for production follow-on.
TEAMING AND PARTNERING STRATEGY
BUILDING THE RIGHT TEAM BEFORE THE ROOM CLOSES
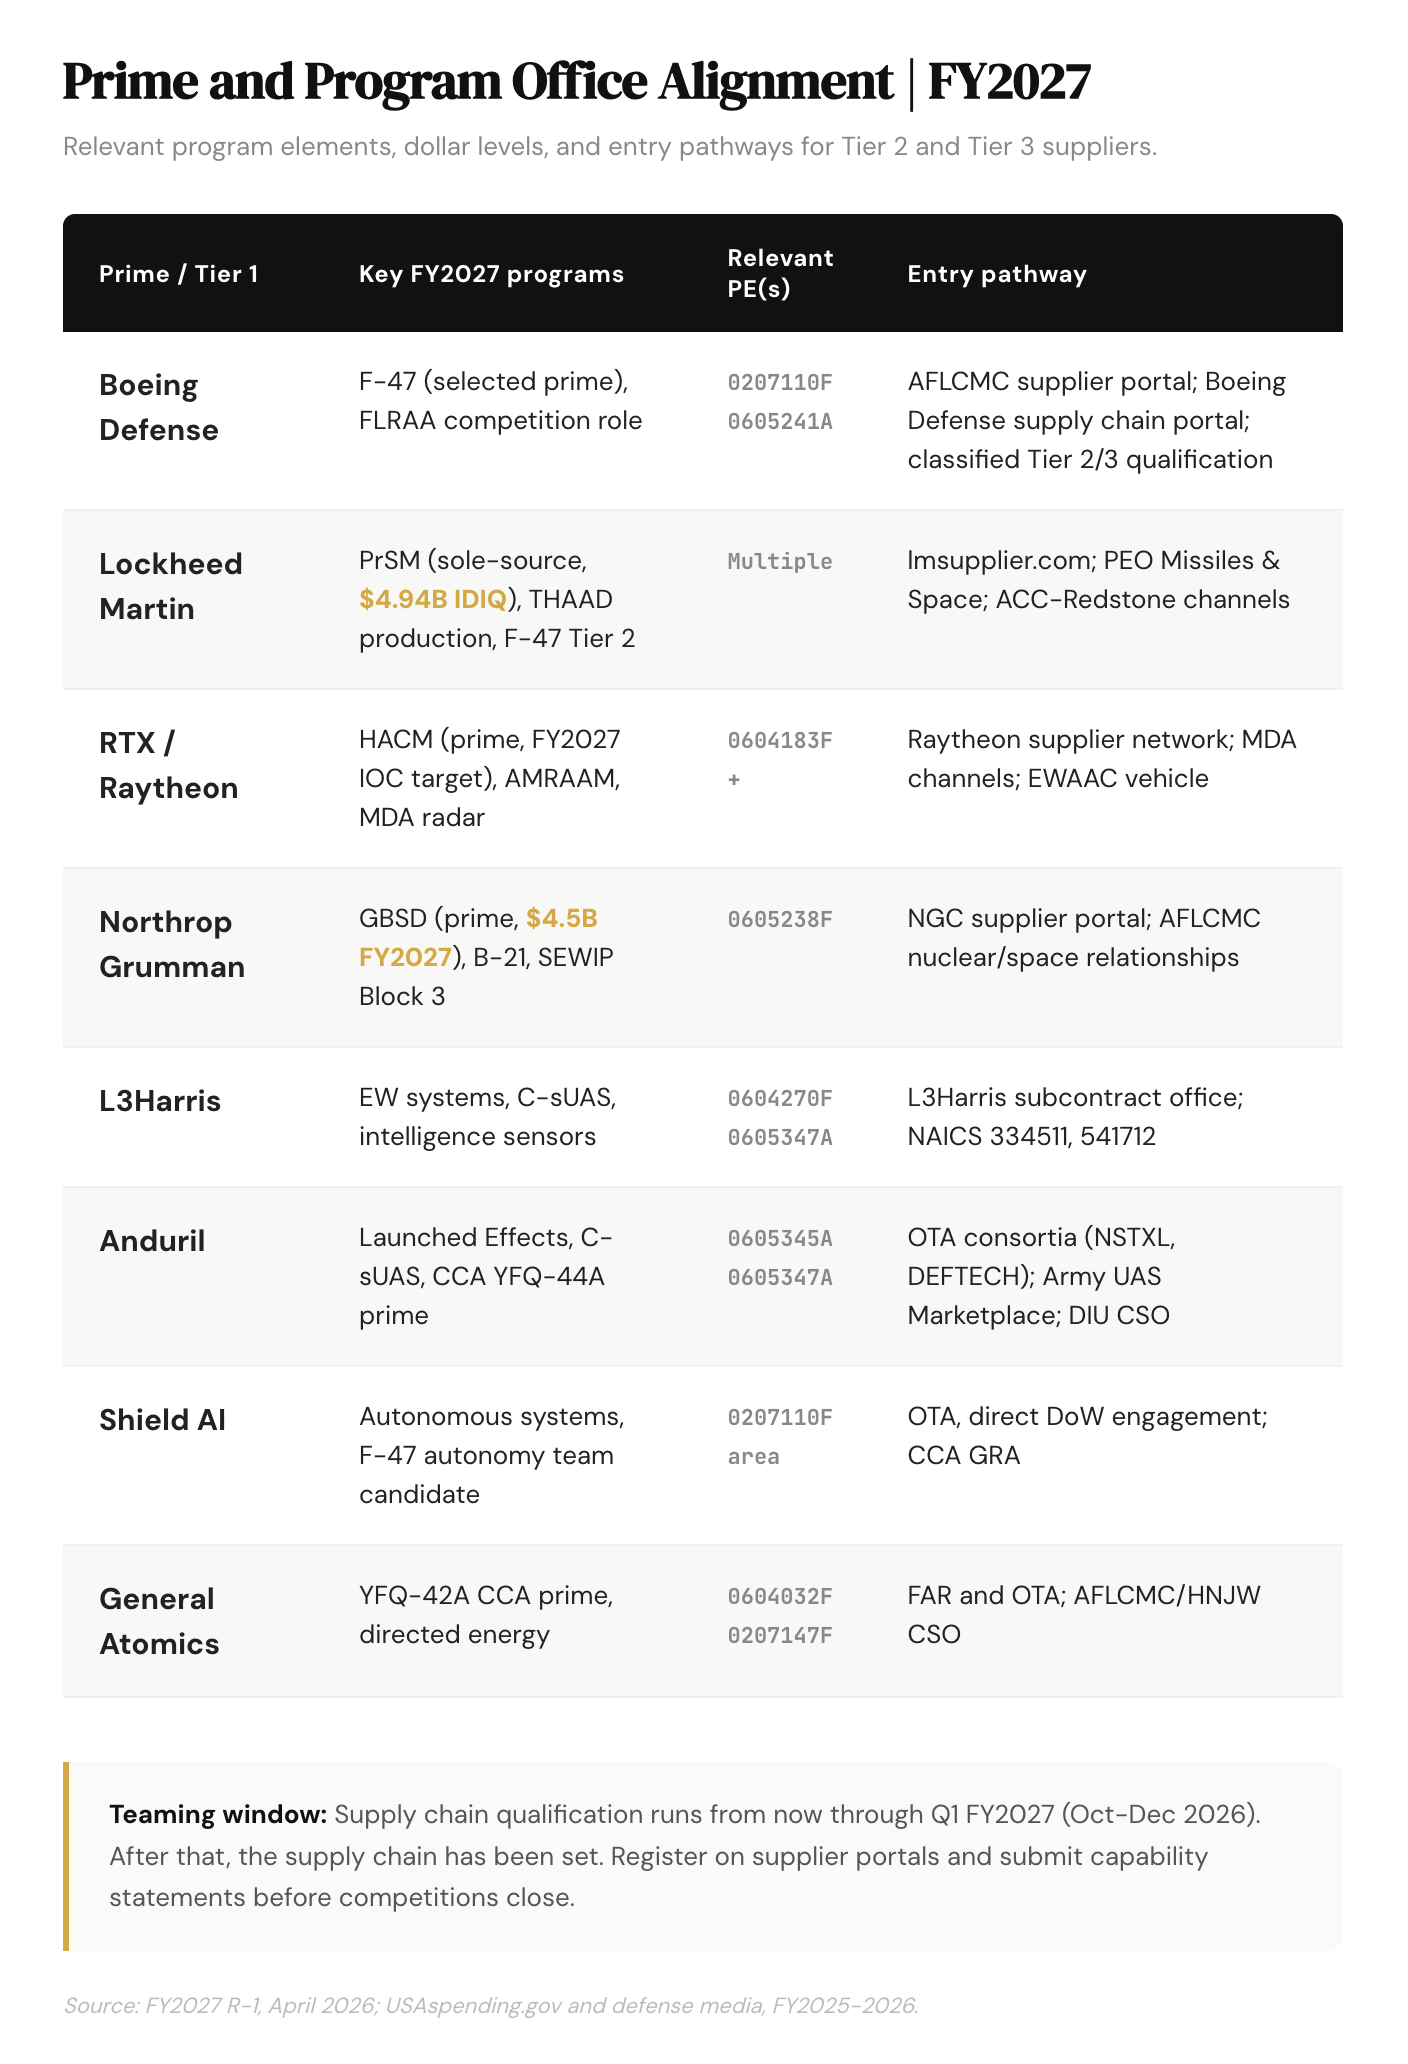
The FY2027 budget books do not just tell you which technologies are funded. They also tell you which prime contractors are positioned to receive the bulk of that funding, and therefore which organizations you need relationships with before competitive awards close. Primes sizing supply chains for the programs in the Landscape Tables are doing it right now. The teaming window for FY2027 priority programs runs from the April 2026 budget submission through the full-rate production decisions and major solicitation closings concentrated in the second half of FY2026 and early FY2027.
The signal here: The supply chain picture this year is more complex than usual because several programs are simultaneously at transition points. Collaborative Combat Aircraft FY2027 funding reflects the production transition. The CCA Increment 1 production decision is targeted for summer 2026, which means Anduril and General Atomics are qualifying subsystem suppliers right now. The FLRAA Future Long Range Assault Aircraft budget reflects acceleration: the MV-75 is heading toward a Critical Design Review in 2026 with physical prototype delivery targeted for FY2027. The F-47 EMD program at $7.4B combined is building out its Tier 2 and Tier 3 supply chain while most of the details remain classified. And the Golden Dome SHIELD IDIQ, at $151B over 10 years, is already open with 2,100+ awardees; the question now is who captures task orders, not who gets on the vehicle.
The January 7, 2026 Executive Order creates a non-obvious opening. “Prioritizing the Warfighter in Defense Contracting” requires underperforming contractors to submit board-approved remediation plans within 15 days and prohibits stock buybacks and dividends until delivery performance improves. A company that can demonstrate throughput capacity, not just technical capability, but production certification, past performance, and surge-ready manufacturing, is a different conversation partner than one with a pitch deck. The EO changed the incentive structure. The teaming opportunity follows from that change.
Why This Matters
Primes building supply chains for programs at the 6.5 (System Development and Demonstration) and 6.7 (Operational System Development) stage are operating under real schedule pressure. The CCA Increment 1 production decision is a defined milestone. The FLRAA prototype is a committed FY2027 deliverable. The GBSD program at $4.5B is in full-rate SDD and heading toward the Sentinel ICBM’s first operational deployment window. These programs are not running open competitions for every component. They are qualifying suppliers against capability and capacity requirements and closing their teams. The window runs from now through approximately Q1 FY2027 (October-December 2026). After that, the supply chain has been set.
How to Apply It
Contact the small business program office for each prime aligned to your target programs. Request a capabilities briefing. This is a standard, accepted outreach channel. Lead with production capacity data and certifications, not company narrative. The questions primes are asking right now are: Can you surge? Are you certified? Do you have past performance?
Register on the supplier portals for the primes aligned to your target programs before solicitations open. Boeing Defense’s supplier portal, lmsupplier.com for Lockheed Martin, and NGC’s supplier portal all have onboarding timelines. Supplier qualification takes time.
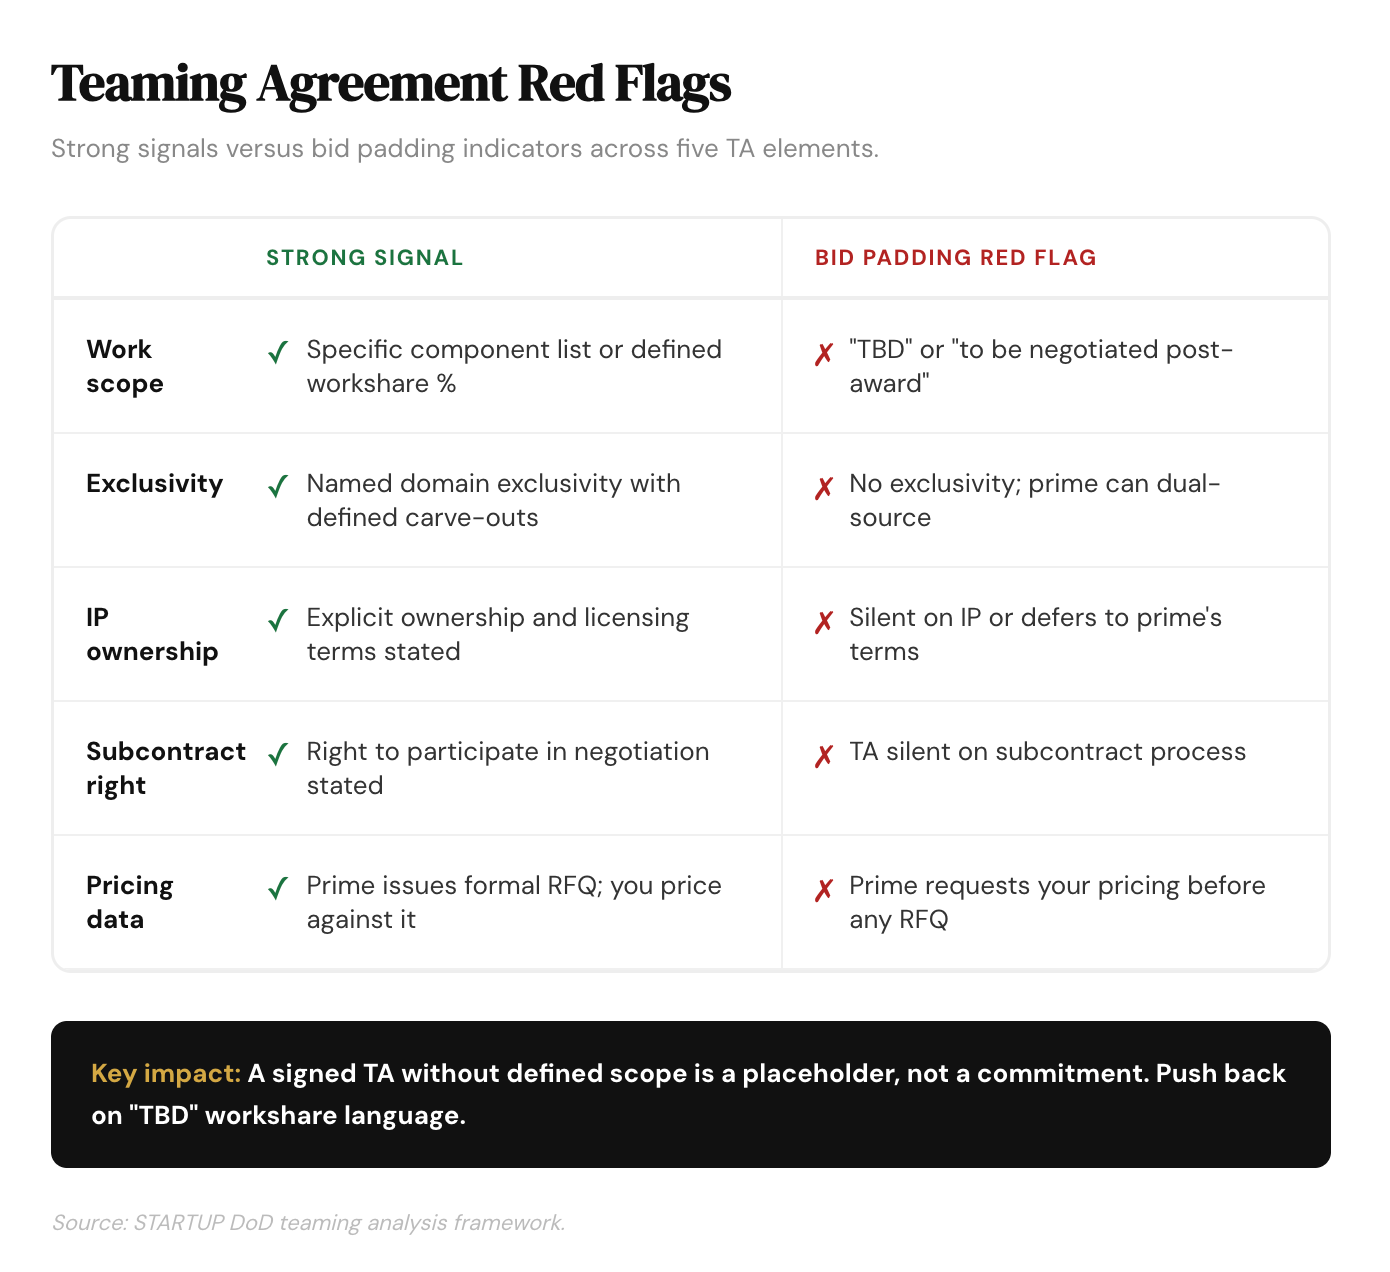
Push back on any teaming agreement that lacks defined scope. A TA without a specific workshare percentage or component list is a placeholder, not a commitment. If the prime will not define scope at signing, citing “competitive sensitivity” or “pending RFP terms,” treat the agreement as contingent at best.
COMPLIANCE AND CAPITAL
THE PACING CONSTRAINTS NOBODY ANNOUNCES
Compliance readiness is a competitive differentiator, not a formality. I am going to say that directly because most companies treat this as a back-office problem to be solved after they win something. That sequence is backwards. For the programs in this analysis, the compliance requirements are specific, sequential, and time-consuming.
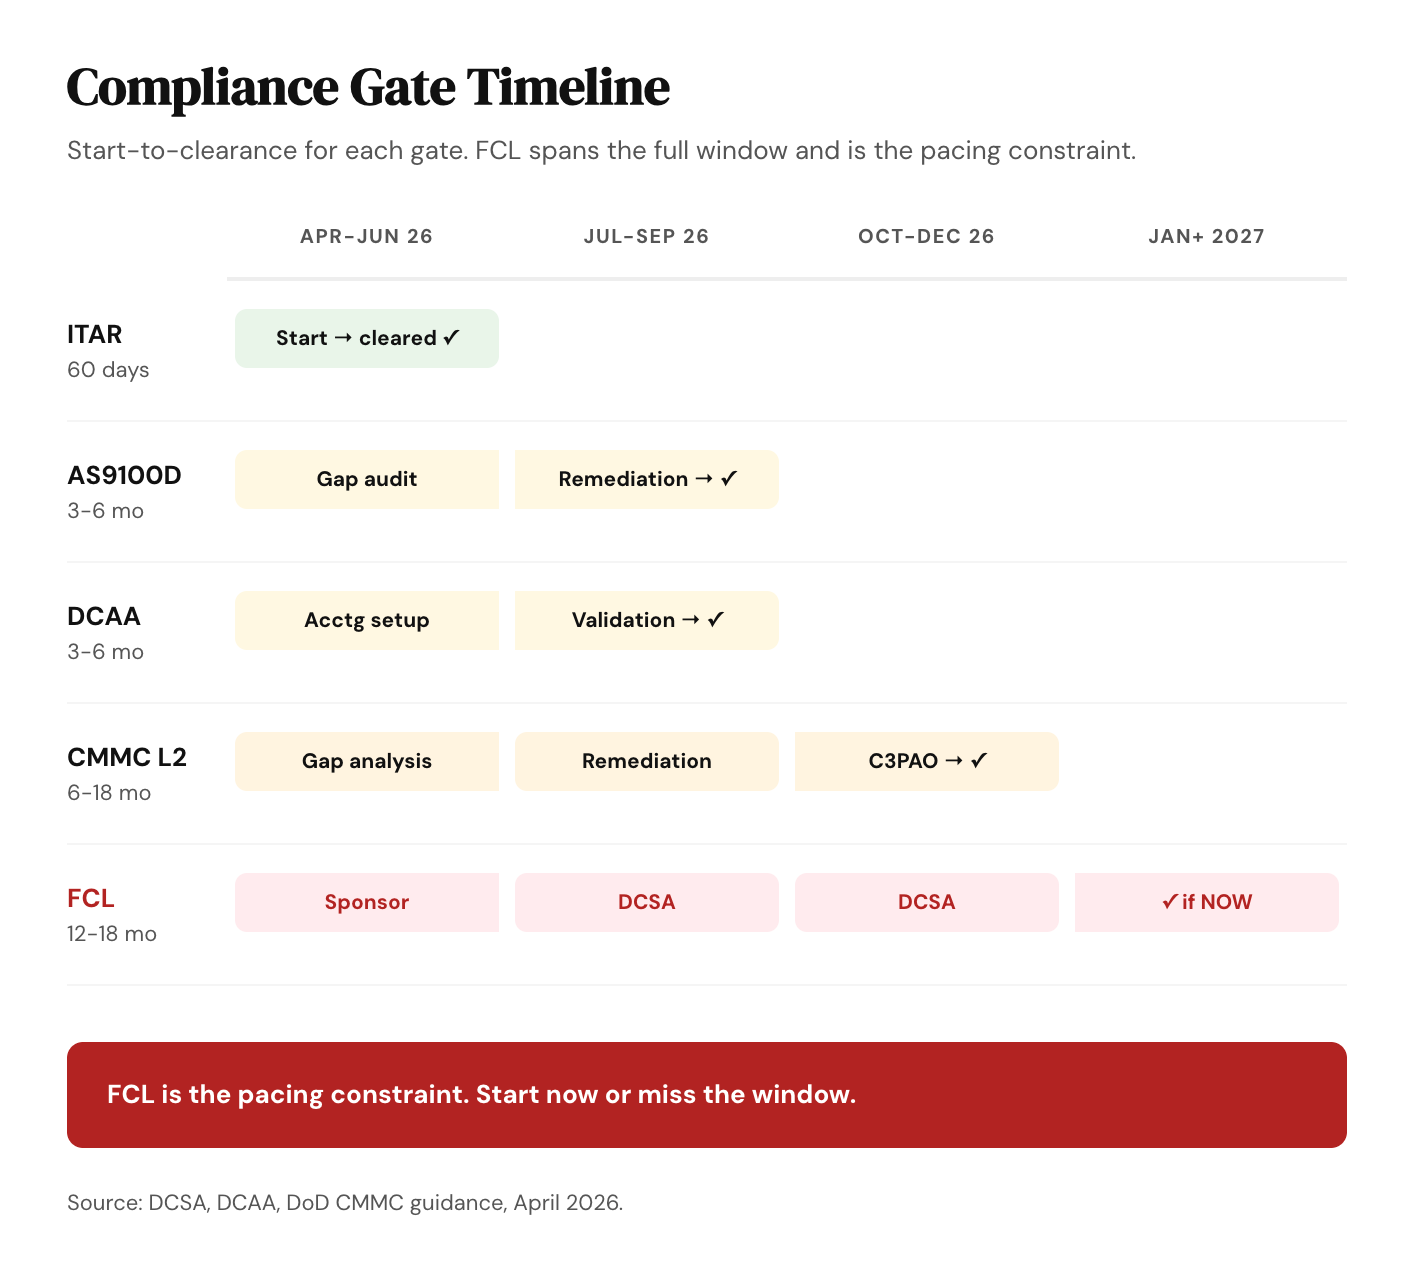
A company without an active Facility Clearance cannot access classified program elements, and a significant portion of the highest-funded programs in this budget, including F-47 (PE 0207110F, $7.4B), classified Space Force lines, and Golden Dome architecture programs, have classified elements that require FCL access before you can even receive the technical data. A company without CMMC Level 2 assessment cannot handle Controlled Unclassified Information on development programs that require it. A company without ITAR registration cannot receive technical data on USML Category I (aircraft) or Category IV (missiles) items. A company without an accounting system that can support cost-type subcontracts cannot participate in many of the development programs in this analysis without significant remediation.
If you are reading this in April 2026 and you have not started the FCL process for a program with classified elements, your earliest realistic access is mid-to-late 2027, after the teaming windows for the programs in this analysis have already closed.
Federal Capital Available Now
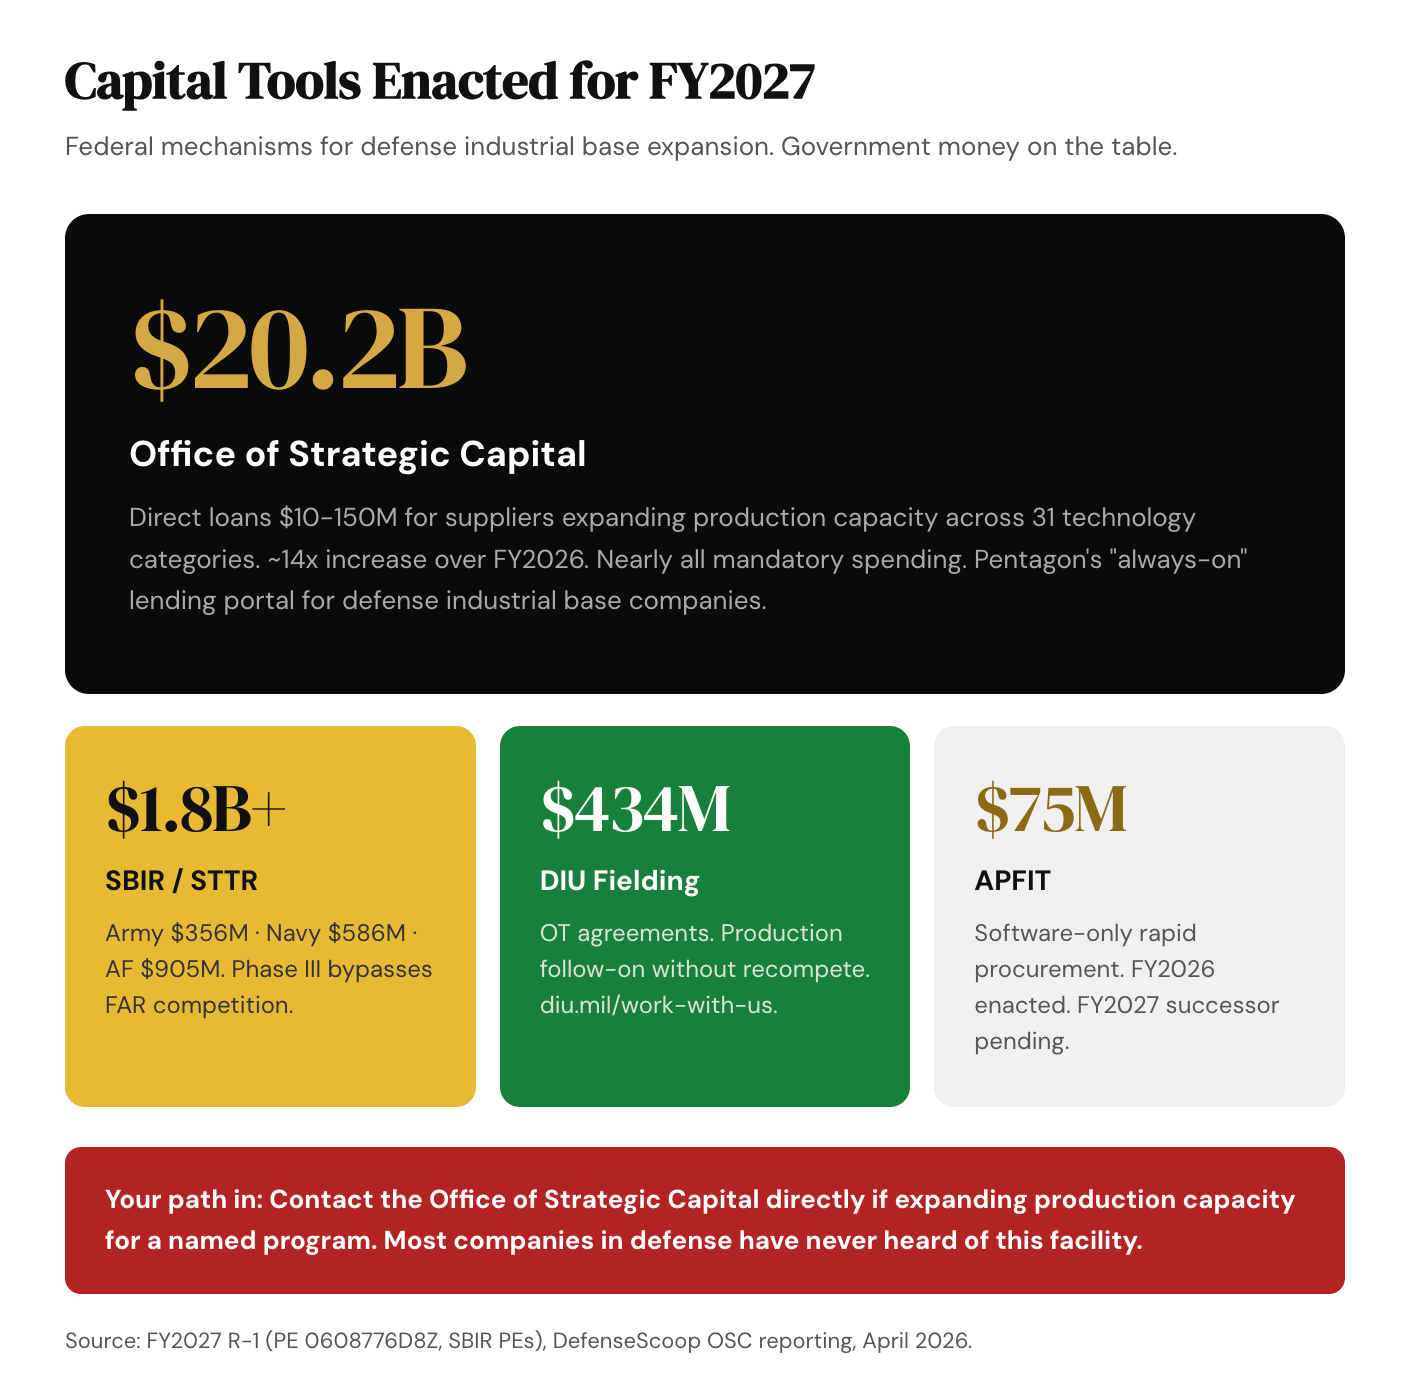
Compliance readiness costs money and takes time. These four mechanisms exist specifically to fund that ramp. Most companies in the defense market have never used any of them.
Why This Matters
The SBIR program across all three services represents the largest direct funding pathway in this budget for companies that do not have a prime teaming agreement. Army SBIR at $356M, Navy SBIR at $586M, and Air Force SBIR at $905M are line items in the R-1, not aspirational numbers, but funded program elements. SBIR Phase II awards average $1-3M. Phase III, when SBIR-funded technology is adopted by an operational program, does not require a new competition and is not subject to the FAR full-and-open competition requirements that govern most defense contracts. That is the mechanism. SBIR Phase II to operational program Phase III is the non-prime pathway most companies never fully exploit.
The compliance gates above are not theoretical. They are the specific barriers I have seen slow or eliminate companies that had the right technology but the wrong operational readiness. ITAR registration can be done in 60 days. DCAA audit readiness with the right accounting system takes 3-6 months. AS9100D takes 3-6 months. CMMC Level 2 is 6-18 months. FCL is 12-18 months. None of these can be compressed on short notice by talent or urgency. They run on their own timelines. The only variable you control is when you start.
How to Apply It
Evaluate OSC loan and guarantee eligibility if you are expanding production capacity or developing capabilities in any of the 31 covered technology categories. The program is underutilized relative to its authorization. Loan sizes of $10-150M are appropriate for manufacturing buildout, tooling investment, and facility expansion tied to named FY2027 programs.
Start the FCL sponsorship process immediately if any of your target programs have classified elements. This means identifying a prime contractor willing to sponsor your company through the DCSA process. The 12-18 month FCL timeline means the earliest you can access classified program data is 2027 if you start today.
Apply for SBIR/STTR defense 2027 funding in topic areas that align with your technology and the R-1 program elements from Stage 2. The DSIP portal (dsip.osd.mil) is the central entry point. Match your technology to open topics against the PE numbers, not against marketing language. Defense SBIR funding in 2027 is concentrated in EW, autonomous systems, space, and AI/ML.
BUILDING YOUR ADVANCED OPPORTUNITY PIPELINE
CONNECTING HISTORICAL DATA TO FUTURE BUDGETS
The pipeline construction stage is where this analysis converts from information to competitive positioning. Most BD pipelines I see in the defense market are built backwards: companies find an RFP, respond to it, and then work to understand the program after they are in the competition. By that point, the incumbent relationship has been established, the requirements have been shaped by others, and the supply chain team has largely been assembled.
The FY2027 budget books give you a different starting point. They tell you, at program element granularity, which programs are funded and at what level, before the solicitations are written.
The framework is straightforward: if a program element has a major FY2027 increase AND an existing contract vehicle that generates task orders, the next task orders from that vehicle are your near-term opportunities. If a program element has a major FY2027 increase but no established vehicle, the likely outcome is a new solicitation in Q1-Q2 FY2027 (October 2026 - March 2027). Both patterns are visible in the data right now.
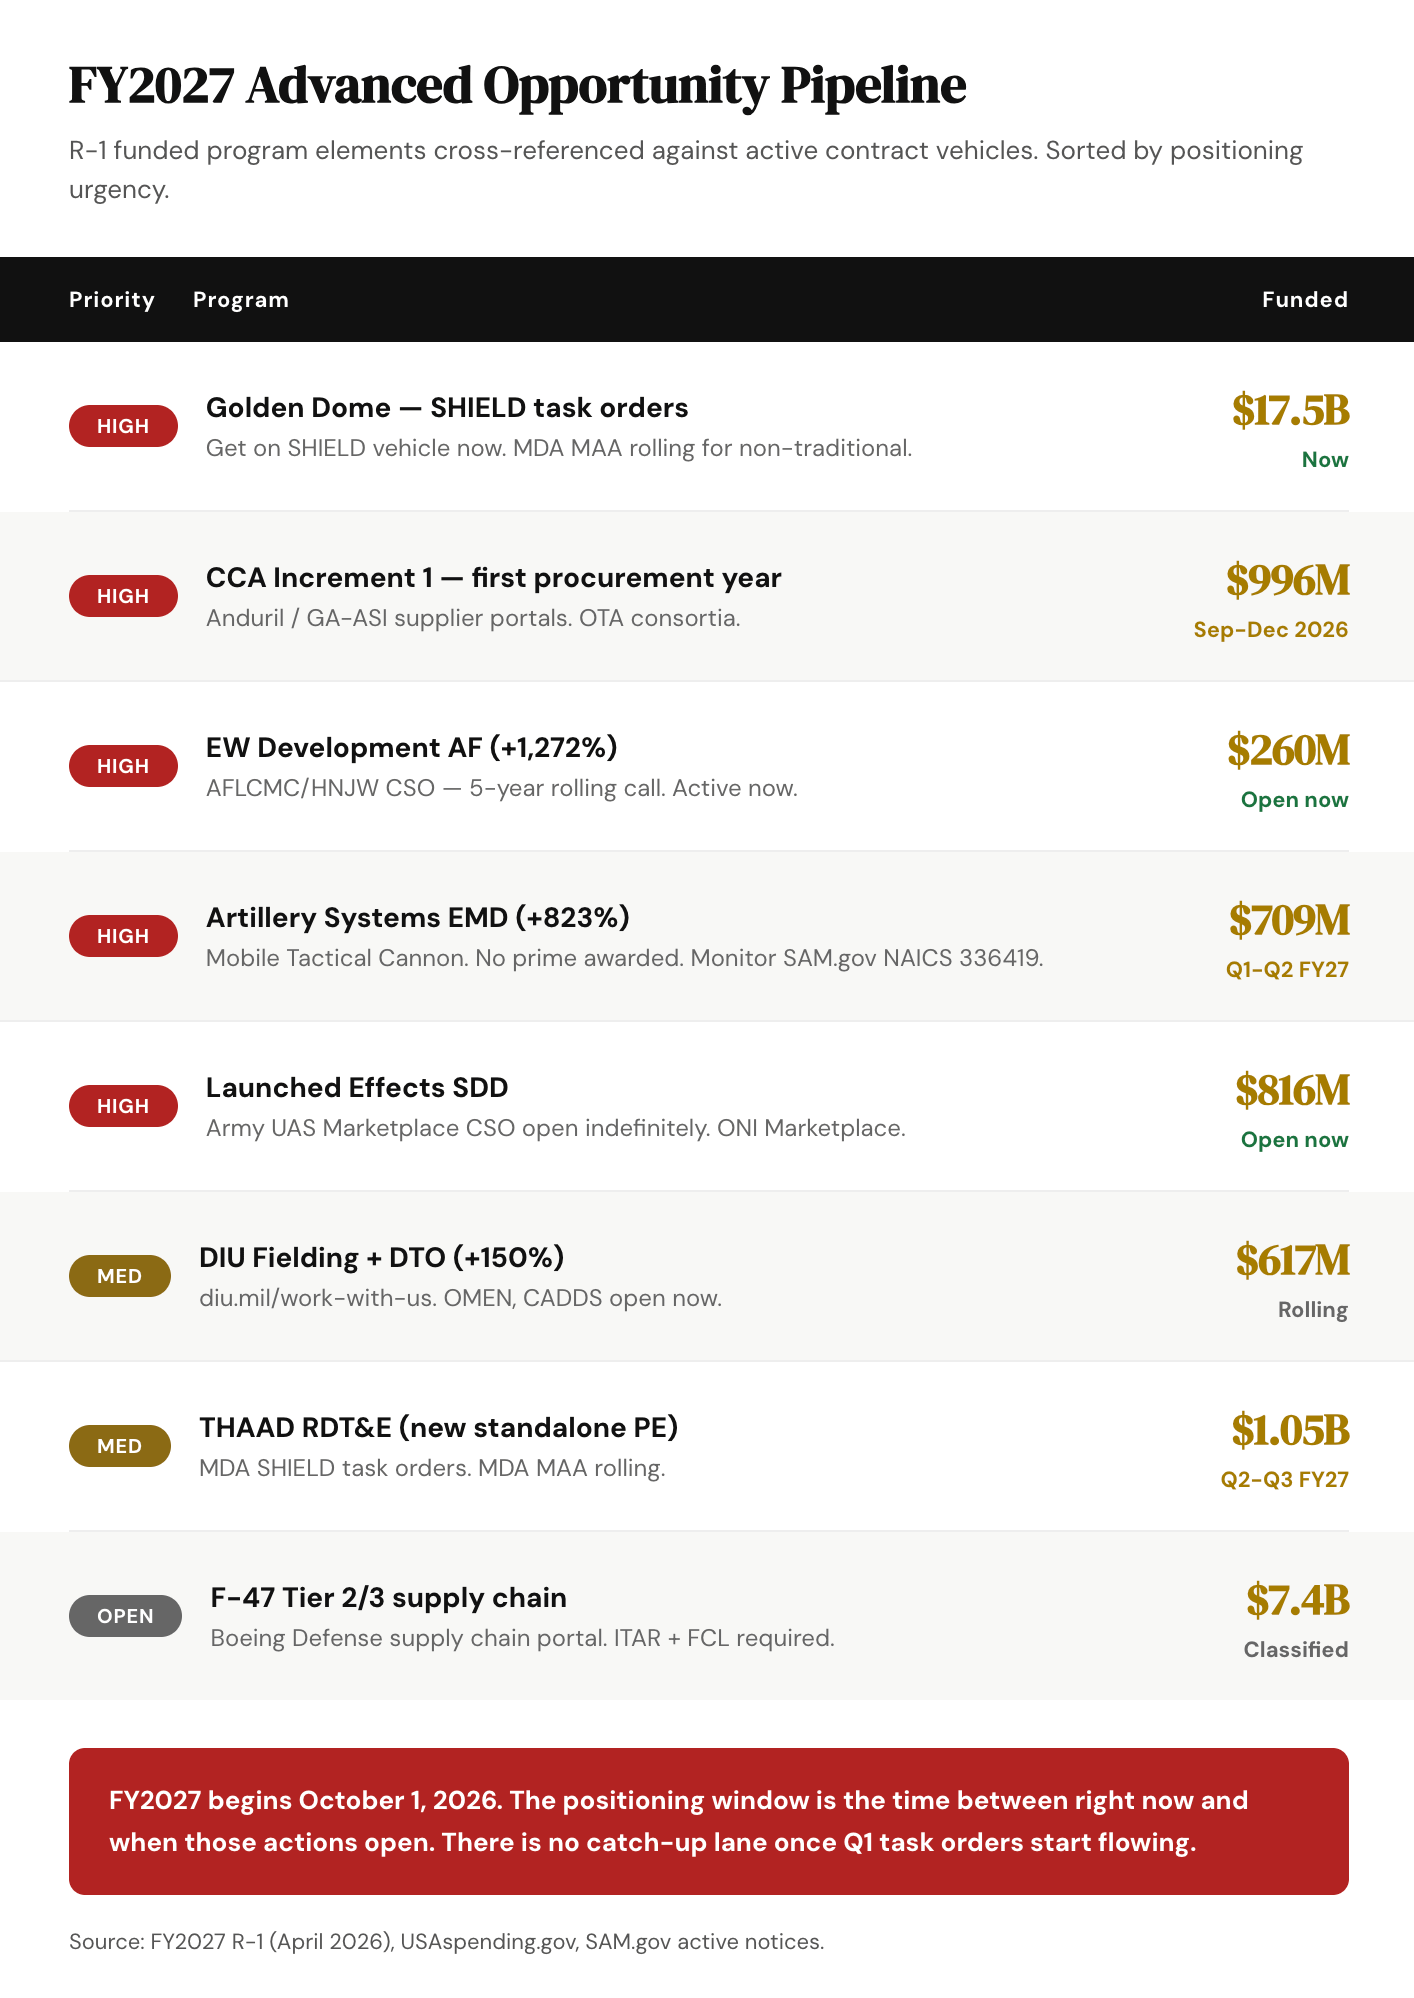
A pipeline built on budget data and historical award analysis is structurally different from a pipeline built on RFP responses. The former gives you 6-12 months of positioning runway before competition opens. The latter puts you in a reactive posture against incumbents who have been shaping the requirements for months.
Note on the SHIELD IDIQ: The MDA SHIELD vehicle (HQ0859-25-R-E001) has 2,100+ awardees and a $151B ceiling over 10 years with no baseline funds obligated at the IDIQ level. All obligations happen at task order level, competed among awardees. If you are not on the SHIELD vehicle and you are targeting any Golden Dome or missile defense program element, that needs to be the first call you make. There is an on-ramp process. Use it.
Note on the Army UAS Marketplace CSO: This is posted indefinitely through PEO Aviation / PMO UAS at ACC-Redstone. It covers UAS platforms, payloads, autonomy software, EW sensors, ISR systems, and communications, the full UAS ecosystem for the Launched Effects SDD program element (PE 0605345A, $816.4M). Awards can be FAR or OT. It is open now and it is the direct entry path for the highest-funded Army autonomous systems line in this budget.
Why This Matters
FY2027 begins October 1, 2026. That is five months from the April 2026 budget submission. The programs in this pipeline with Q1 FY2027 solicitation windows, Artillery Systems EMD, CCA production, MDA SHIELD task orders, will begin their competitive processes before most companies have finished reading the budget headlines. The positioning work for those opportunities is not a FY2027 task. It is happening right now.
Three patterns to internalize from this pipeline: First, existing IDIQ vehicles (SHIELD, EWAAC, Army UAS Marketplace) are already open and generating task orders, the entry question is not “when does this program release an RFP?” but “how do I get on the existing vehicle?” Second, programs with 50%+ YOY increases and no existing vehicle are your Q1-Q2 FY2027 competitive opportunities, build the capability statement, the teaming agreement, and the compliance credentials before October. Third, the programs labeled [OPEN] require classified access or Boeing prime qualification before you can compete. If those are your targets, the FCL and supply chain qualification timelines in Stage 5 are your actual pacing constraint, not the solicitation window.
How to Apply It
Export USAspending.gov award data for your target NAICS codes from FY2025-FY2026 to a spreadsheet. Filter by contracting office using the PIID prefixes in Stage 1 (W58RGZ for PEO Aviation, W31P4Q for ACC-Redstone, FA8601/FA8681 for AFLCMC). Sort by recipient. This is your competitive baseline.
Tag each active SAM.gov notice with the corresponding FY2027 PE number and funding level from the R-1. This gives you a relevance ranking. Opportunities tied to PEs with major funding increases, EW Development at +1,272%, Artillery Systems EMD at +823%, Counter-UAS at +156%, are higher priority than those tied to flat or declining lines. Work the ones with momentum.
Set a hard calendar trigger for October 1, 2026, the start of FY2027. The programs that received major FY2027 budget increases will begin issuing solicitations and task order competitions in Q1 FY2027. Your positioning work, teaming agreements, compliance certifications, supplier portal registrations, SHIELD task order readiness, needs to be complete before that date. There is no catch-up lane once Q1 task orders start flowing.
STRATEGIC CONSIDERATIONS
Six higher-order factors that should shape how you approach this budget, independent of which specific program or stage you are entering from:
1. F-47 at $7.4B is the largest new PE in this budget and the least accessible.
Boeing is the prime. The contract is classified, cost-plus, managed through AFLCMC. The realistic entry point is Tier 2 or Tier 3: avionics, composites, propulsion, sensors. Boeing is building a supply chain for approximately 185 aircraft through LRIP and FRP. That qualification window is running now, not after a subcontract announcement. Start on Boeing’s supplier portal and FCL in parallel.
2. Artillery Systems EMD at $709M is the most underreported signal.
PE 0604854A went from $76.8M to $709.2M, a 9x increase. The driver is the Mobile Tactical Cannon replacing the cancelled ERCA. No prime has been awarded. This will generate several billion in production competition behind it. If you are in precision fires or artillery systems, this is the first priority pursuit in this budget.
3. Space Force O&M at $9.7B is creating a contractor logistics opportunity nobody is tracking.
The RDT&E number will get the attention. But O&M grew 64% and approximately $2.1 billion is contractor logistics and system support. That is recurring services spending. The vehicle is Space Systems Command in El Segundo. NAICS 541614, 541690, 517720. Build SSC relationships now.
4. Golden Dome’s mandatory appropriation operates differently from everything else.
$17.5 billion in mandatory RDT&E (Account 3007D) is not subject to the annual appropriations process or CR risk. The money is more predictable than discretionary funding. The contracting vehicle is MDA SHIELD ($151B, 2,100+ awardees) and the MDA MAA (HQ0860-25-S-0001) for non-traditional vendors. Both are active now.
5. SBIR at $1.8B+ is the largest non-prime entry pathway in this budget.
Army $356M. Navy $586M. Air Force $905M. Most companies use SBIR as grant funding without connecting it to program transition. The mechanism is Phase III: when a program office adopts SBIR-funded technology, that adoption does not require a new competition (15 U.S.C. § 638). A Phase II win in an EW topic tied to PE 0604270F (+1,272%) converts directly into a sole-source follow-on. Identify the fastest-growing PEs from this analysis, then find the corresponding SBIR topics.
6. DTO at $183M (+150%) and DIU at $434M are where the DoW wants commercial companies to enter.
Combined: approximately $617M in FY2027 specifically for commercial technology companies to enter without a FAR-based prime contract. The CSO process: submit a white paper at diu.mil/work-with-us, negotiate an OT prototype, convert to production without recompete. Active CSOs include OMEN at AFLCMC (deadline April 15, 2026) and CADDS. Monitor diu.mil directly. CSO notices post there before SAM.gov.
TO WRAP UP
The FY2027 President’s Budget is the most precise publicly available demand signal the Department of War publishes. $343.7 billion in RDT&E. $430.7 billion in O&M. A new $17.5 billion mandatory appropriation structure that has no precedent at this scale. The programs are funded, the program elements are numbered, and the contract vehicles are either active or coming. The positioning window runs from now through Q1 FY2027 (October-December 2026). After that, supply chains are set, teaming agreements are locked, and the competitive landscape is fixed for the duration of the program.
The signal here: The FY2027 NDAA has not been enacted. Congress will hold authorization and appropriations hearings through spring and summer 2026, mark up the request, and pass or not pass the defense appropriations bill before October 1. Some programs in this analysis will change. The Golden Dome mandatory appropriation structure is particularly likely to generate congressional debate, both on the substance of the funding level and on the precedent of insulating major programs from future appropriations control. The reconciliation package that funds the $350 billion mandatory request still requires simple majority passage. It is not guaranteed. But the signal embedded in what the executive branch asked for, at the program element level, is already the clearest demand map this department has ever published. That signal does not require enactment to be useful. It requires reading.
Three things I am still watching: whether Congress adjusts the Golden Dome mandatory appropriation structure in the NDAA markup, specifically whether it accepts the funding moat or imposes conventional oversight; whether the F-47 contract structure is disclosed publicly or remains classified through the FY2027 execution year, because that disclosure determines the Tier 2/3 qualification timeline; and how the Artillery Systems EMD funding gets obligated and to whom, specifically whether the Mobile Tactical Cannon is a competitive award or a directed development.
How to Use This
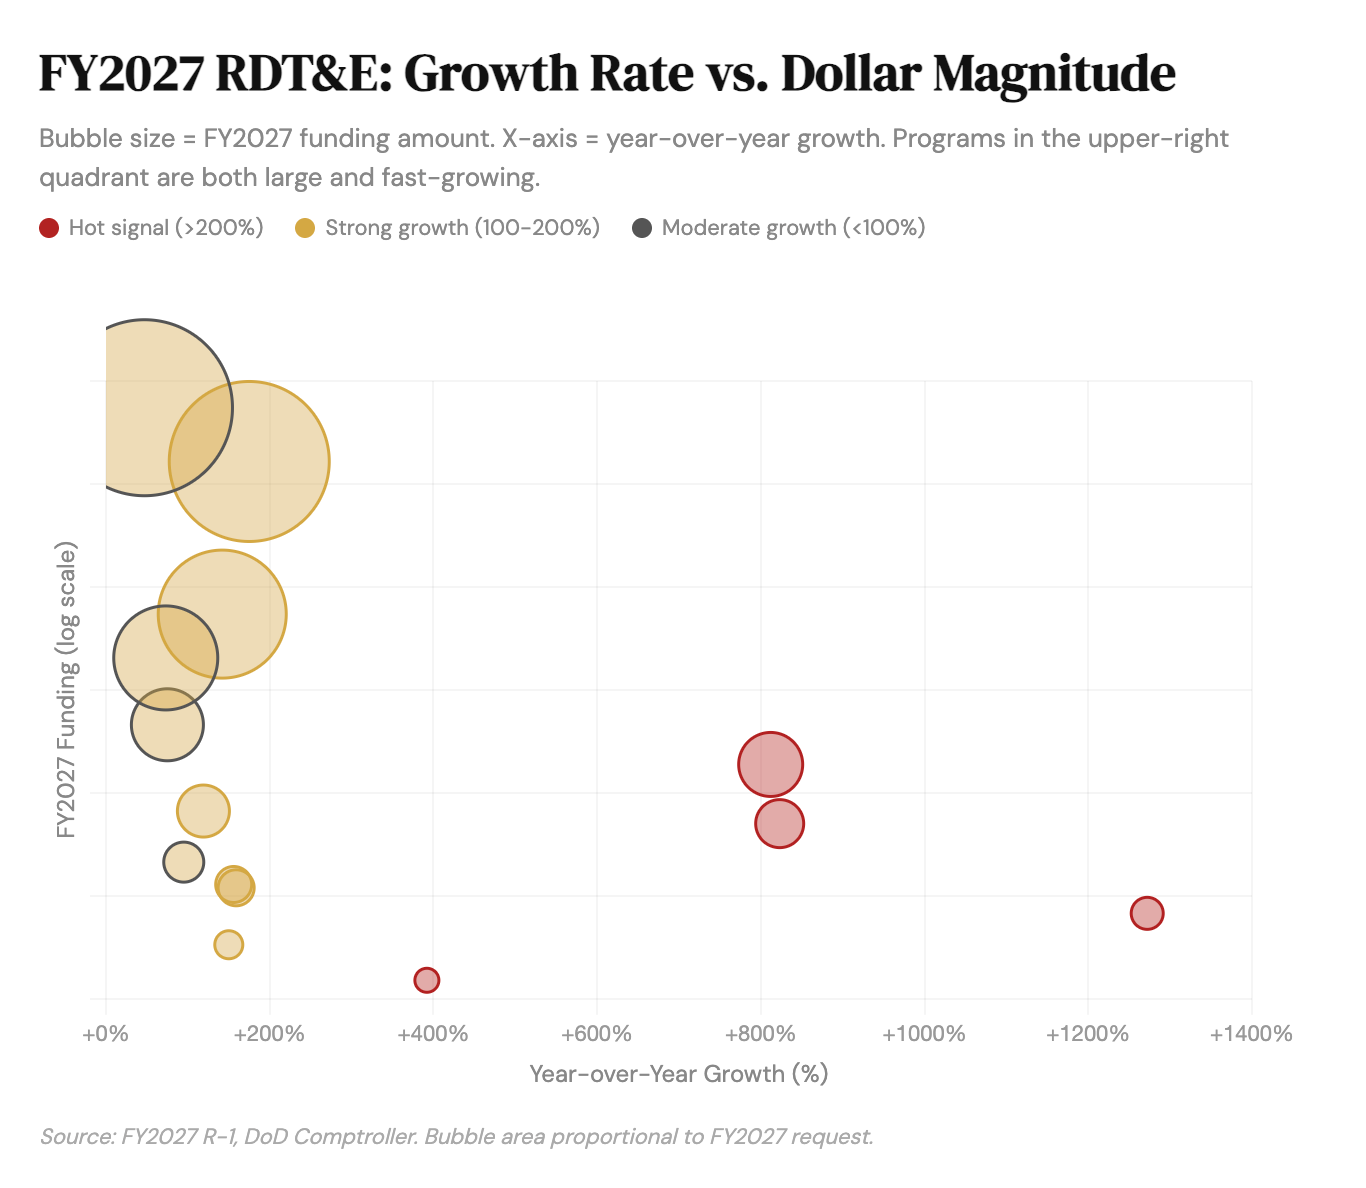
Use the signals table and bubble chart as your market sizing baseline. Use the technology domain mapping and program-to-market map to translate your capabilities into funded PE numbers. Use the SAM.gov filter stack to monitor before postings appear. Use the prime alignment table and teaming red flags to find the right rooms and avoid placeholder agreements. Use the compliance gate timeline to set your internal readiness calendar. Use the pipeline dashboard as a ranked pursuit list built on budget data, not RFP responses. Replace the R-1 figures with enacted amounts as soon as the FY2027 defense appropriations bill lands.
Limitations
This analysis draws entirely on publicly available sources as of April 2026. Budget figures come from the FY2027 President’s Budget Exhibit documents (M-1, O-1, RF-1, R-1) released by the Office of the Under Secretary of War Comptroller. Program element funding figures are in thousands of dollars as published. I have not analyzed the P-1 (Procurement) or C-1 (Military Construction) exhibits in depth in this issue. Those are the next layer of specificity, particularly for production-scale companies looking at PrSM unit buys, THAAD procurement, and Space Force infrastructure buildout. The P-1 will show exactly how many units are planned, at what unit cost, under which contracts. That is the next issue.
Building This Playbook Together
If you see data I missed, a source that conflicts with something I cited, or a program angle I did not cover, I want to know. This analysis sharpens with input from people working inside these programs and supply chains. The newsletter is better when the community contributes to it.